An insurer’s promise matters only if it can pay claims after a difficult year. In the United States, that promise depends on financial resources, the risks a company takes, and oversight by state regulators.
Insurance Capital Adequacy Requirements help frame how regulators assess an insurer’s ability to meet claims and other obligations. We’ll explain how state oversight and risk exposure shape that assessment, and how newer NAIC rules affect certain investments. The goal is a clearer way to judge what capital figures can tell us about an insurer.
Key Takeaways
- Reserves cover expected claims; capital can absorb worse-than-expected losses.
- U.S. insurers use separate RBC formulas for life, health, and property/casualty business.
- RBC supports regulatory review but is not a stand-alone financial-strength rating.
- State licensing minimums and ongoing RBC monitoring serve different purposes.
- Investment type and collateral can change an insurer’s required capital.
- We should check an insurer’s latest statutory information and applicable state rules.
We can assess that promise by looking at both the risks an insurer carries and the resources available to absorb losses.
What Is Capital Meant to Protect?
Reserves provide for expected claims, while capital gives an insurer a buffer when actual losses are worse than expected. Risk-based capital (RBC) is a formula that sets an insurer’s required capital according to the risks it carries.
Reserves are liabilities for expected obligations, such as claims tied to policies already issued. Capital is the excess resource that can absorb adverse outcomes without leaving policyholders unpaid. Reserves and capital protect against different parts of an insurer’s financial risk.
We cannot judge solvency by looking at one balance-sheet figure. The International Association of Insurance Supervisors calls for solvency assessment to consider assets, liabilities, capital requirements, and capital resources together.
Assess the whole balance sheet: assets, liabilities, capital needs, and available resources affect one another.
An insurer may hold valuable assets, yet face large obligations or assets that are hard to turn into cash. Technical provisions, which include expected policy obligations, also shape the picture. Their value depends on the claims and other payments the insurer expects to make.
That is why a capital figure has meaning only beside the obligations it must support. Check both the liabilities and the resources available to meet them, since a strong-looking capital figure cannot repair inadequate reserves.
How Does the U.S. Risk-Based Capital Framework Work?
U.S. regulators use different RBC formulas for life, health, and property/casualty insurers rather than applying one identical calculation to every company. Each model reflects the business and risks that an insurer takes on.
The required RBC amount is Authorized Control Level (ACL) RBC. Regulators compare an insurer’s available capital, called Total Adjusted Capital (TAC), with the amount produced by its formula.
Separate RBC formulas for life, health, and property/casualty insurers
Life insurers, health insurers, and property/casualty insurers use distinct risk-based capital formulas. Each model weighs exposures in ways suited to its policies, assets, and expected obligations.
The results help regulators spot weak capital positions, but they do not replace other forms of review. RBC requirements act as a supervisory reference, not a complete account of every risk.
How capital shortfalls trigger regulatory action
As capital weakens, regulatory responses can become more forceful. The four action levels, from less to more forceful, are:
- Company Action Level, which calls for an insurer plan to address its capital position.
- Regulatory Action Level, which allows stronger regulatory review and action.
- Authorized Control Level, which gives regulators authority to take control in defined conditions.
- Mandatory Control Level, which requires regulatory control under the applicable rules.
Regulators may also consider these records and reviews alongside RBC:
- Statutory financial statements that report the insurer’s financial position.
- Examinations that review the insurer’s practices and records.
- Reserve oversight, including review of the insurer’s expected obligations.
- Insurer risk assessment that considers broader business exposures.
Those checks can add facts that a formula alone cannot show. Treat an action level as a prompt for regulatory scrutiny, not as a complete description of an insurer’s financial condition.
Which Risks Drive an Insurer’s Capital Needs?
The main capital drivers change with the promises an insurer makes and the assets it holds. Different business lines create different patterns of risk, even when insurers hold similar investments.
Life RBC groups exposures into C-0 through C-4 components. Property/casualty RBC looks closely at claims, pricing, catastrophe exposure, asset values, and growth.
Life insurer exposures
Life RBC includes C-0 affiliate risk, such as exposure to related companies. C-1 covers investment and asset risks, while C-2 captures insurance risks tied to claims.
C-3 includes interest-rate risk, which can arise when asset income and policy obligations respond differently to rate changes. C-4 covers general business risk, including other risks from running the insurer.
These categories reflect the varied promises made by life policies. An insurer’s mix of products and investments can change the weight of each exposure.
Property/casualty insurer exposures
Property/casualty insurers face underwriting risk when premiums fail to cover claims and expenses. Their RBC calculations also account for claim reserves that may prove inadequate and pricing that does not match losses.
Catastrophe exposure can create large claims in a short period. Asset-value changes may weaken the investment side of the balance sheet, while rapid growth can strain pricing, claims review, or management systems.
Asset, credit, underwriting, and interest-rate risks can affect more than one line of business. Match the risk analysis to the insurer’s business mix instead of assuming every line creates the same capital exposure.
How Should We Read an RBC Ratio?
An RBC ratio compares an insurer’s available statutory capital with the capital amount produced by its applicable formula. For life insurers, the ratio is Total Adjusted Capital divided by Authorized Control Level RBC.
RBC is designed to help regulators identify potentially weakly capitalized companies, not to rank insurers by financial strength. The ratio is a supervisory signal within a wider evaluation.
Two insurers with similar ratios may have different products, assets, or risks. A direct comparison can hide those differences, so the number is not a stand-alone credit rating.
Statutory RBC also differs from internal capital evaluations and rating-agency capital models. Those methods may use different assumptions or goals, so their results do not match by default.
When we compare insurers as consumers, we can also check financial-strength information and complaint records alongside coverage and price. Guides to comparing auto insurance quotes can help us keep those checks in view.
A second consumer comparison can help us weigh company information while comparing coverage for a higher-risk driver. See how to compare high-risk auto insurance quotes without treating price as the only measure.
Use the ratio to flag questions for further review, not to declare one insurer stronger than another without comparable risk and business information.
How Do State Minimums and Deposits Differ From RBC?
A company may need to meet a state’s licensing capital minimum even when that minimum is separate from its ongoing RBC requirement. State rules govern licensing, while RBC helps monitor an insurer’s financial position as it operates.
Paid-in capital and surplus minimums vary by state and insurer type. State insurance departments administer licensing, and the NAIC Uniform Certificate of Authority Application (UCAA) supports applications made to each state.
Statutory deposits are another state-specific requirement. The required amount and permitted assets depend on the applicable state’s instructions, so one state’s rule should not stand in for another’s.
The National Association of Insurance Commissioners (NAIC) has also hosted discussion about why insurance capital rules differ from bank-focused standards. The U.S. Senate hearing on insurer capital regulation records a 2014 congressional discussion, not current state licensing rules.
For NAIC capital and surplus requirements, statutory deposit requirements, and state-specific requirements, we should check:
- The insurer’s state of domicile.
- The intended line or lines of business.
- The state’s current application or deposit rules.
Those details can affect whether a company qualifies to enter a market. Verify the domiciliary state’s current rules for the insurer’s intended lines before relying on a general threshold.
How Do Insurers Manage Capital Beyond the Formula?
Insurers can manage their capital position through business choices as well as through the required formula. Forward-looking planning helps a company test how changing conditions may affect its risks and resources.
An Own Risk and Solvency Assessment (ORSA) adds an insurer-specific view of exposures, risk mitigation, and enterprise risk management. It complements RBC rather than replacing it.
Companies can use stress tests to explore how losses, market shifts, or other pressures might affect capital. Reinsurance can transfer some risk, while risk reduction can limit exposure in a business line or investment.
Insurers can also retain earnings or set internal capital targets. These choices help management plan for risks that a formula may not capture in full.
Common management levers include:
- Reduce exposure by changing products, investments, or business activity.
- Transfer risk through reinsurance or other permitted arrangements.
- Retain earnings instead of distributing them.
- Raise capital when existing resources do not meet internal goals.
A proposed accounting change is not automatically an adopted capital rule. At the NAIC’s 2026 Summer National Meeting, a proposed cap on admitted net negative interest maintenance reserve was 10% of adjusted capital and surplus; it remained exposed and was not adopted at that meeting.
Before treating a proposed accounting adjustment as a current requirement, confirm whether regulators have adopted it.
How Do U.S. Rules Compare With Other Solvency Frameworks?
The United States, the European Union, and Canada all use risk-sensitive capital approaches, but their measures and intervention structures are not interchangeable. Their percentages reflect different goals and calibration methods.
Solvency II sets a Solvency Capital Requirement (SCR) and a lower Minimum Capital Requirement (MCR). Canada’s LICAT framework uses different ratios and tests.
Solvency II in the European Union
Solvency II sets the SCR at a 99.5% confidence level over one year. The SCR is the main capital requirement, while the MCR is a lower threshold with a distinct supervisory role.
Those measures do not translate directly into a U.S. RBC ratio. A shared percentage format does not mean the frameworks use the same test or trigger the same response.
Canada’s LICAT for life insurers
Canada’s Life Insurance Capital Adequacy Test (LICAT) uses a 99% one-year conditional tail expectation, including a terminal provision. Its Total Ratio and Core Ratio place different emphasis on policyholder protection and financial strength.
The Office of the Superintendent of Financial Institutions (OSFI) sets supervisory target ratios of 100% for the Total Ratio and 70% for the Core Ratio. Minimum ratios are 90% and 55%, respectively.
| Framework | Main measure | Calibration or threshold | Jurisdiction |
|---|---|---|---|
| U.S. RBC | Separate RBC formulas | Four action levels | United States |
| Solvency II | SCR and MCR | SCR at 99.5% over one year | European Union |
| LICAT | Total Ratio and Core Ratio | 99% one-year tail measure; targets 100% and 70% | Canada |
LICAT’s target ratios sit above its minimum ratios, which helps distinguish a supervisory target from a regulatory floor. Compare a framework’s calibration and purpose before drawing conclusions from ratios that share a percentage format.
How Do Insurance Capital Adequacy Requirements Apply to Collateral Loans?
For RBC reported as of December 31, 2027, specified collateral loans are charged according to their collateral rather than under the former uniform 6.8% treatment. The collateral type determines which charge may apply.
Mortgage-backed collateral loans with loan-level detail may use the factors for mortgages held directly. Those Schedule BA mortgage factors range from 0.14% for insured or guaranteed mortgages to about 13% for foreclosed loans.
Mortgage-backed collateral loans
Loan-level detail lets the insurer apply the relevant mortgage factor as if it held the mortgages directly. Insured or guaranteed mortgages receive the lowest listed factor, while foreclosed loans receive a much higher one.
Loans backed by partnership interests or residual interests
Loans backed by joint venture, limited partnership, or limited liability company interests have a 30% base charge. Loans backed by residual tranches or interests have a 45% base charge.
| Collateral | Base charge or factor | 111%-less-than-143% overcollateralization | 143%-less-than-200% overcollateralization | At-least-200% overcollateralization |
|---|---|---|---|---|
| Insured or guaranteed mortgages | 0.14% factor | Not applicable | Not applicable | Not applicable |
| Foreclosed mortgages | About 13% factor | Not applicable | Not applicable | Not applicable |
| Partnership interests | 30% | 24%, 20% haircut | 18%, 40% haircut | 15%, 50% haircut |
| Residual interests | 45% | 36%, 20% haircut | 27%, 40% haircut | 22.5%, 50% haircut |
Valuation and overcollateralization conditions
Overcollateralization means collateral value exceeds the loan amount. Reduced charges for partnership and residual-interest collateral require independent verification of collateral value.
An overcollateralization level of at least 111% and less than 143% gives a 20% haircut. At least 143% and less than 200% gives a 40% haircut; at least 200% gives a 50% haircut.
For either collateral type, the haircut cannot exceed 50%. A loan-to-value ratio above 90%, or collateral value without independent verification, means the full 30% or 45% base charge applies.
Collateral loans backed by assets outside the specified mortgage, partnership-interest, and residual-interest categories retain the 6.8% charge. Check both the latest collateral valuation and the loan’s LTV before applying an overcollateralization reduction.
What Changed for CLO Capital Charges?
The adopted CLO factors apply to multiple securitized debt types for RBC reported as of December 31, 2026. The covered investments include collateralized loan obligations, collateralized bond obligations, and collateralized debt obligations.
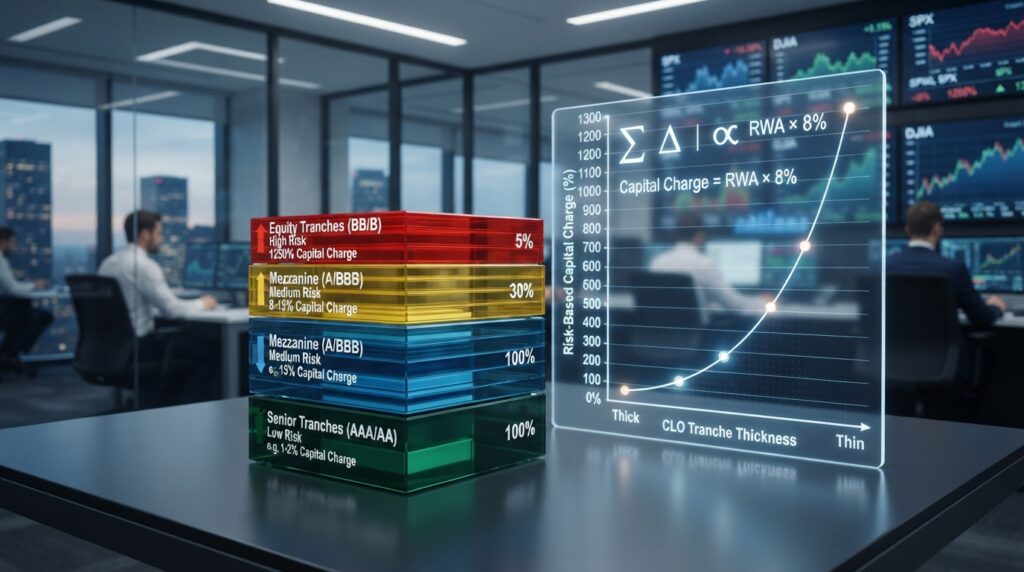
A qualifying broadly syndicated loan CLO tranche can receive an 11.77% pretax surcharge when its thickness is 4% or less. Middle-market CLOs do not receive that surcharge.
Which CLO tranches get the additional charge?
The adopted factors cover broadly syndicated loan and middle-market CLOs, as well as the other listed securitized debt types. CLO residual tranches keep a 45% pretax RBC charge.
The 11.77% pretax surcharge applies to below-investment-grade broadly syndicated loan CLO tranches rated NAIC Designation Category 2.C or below. The tranche must also have thickness of 4% or less.
That surcharge does not apply to middle-market CLOs. The interim NAIC CLO portfolio adjustment factor is 1.0.
How tranche thickness is measured
Tranche thickness is measured from the most recent trustee report available as of the investment reporting date. The measurement does not use the tranche’s thickness at origination.
| CLO exposure | RBC treatment | Thin-tranche surcharge | Thickness reference |
|---|---|---|---|
| Residual tranches | 45% pretax charge | Not stated as applicable | Most recent trustee report on reporting date |
| Qualifying broadly syndicated loan tranches | Applicable adopted factor | 11.77% pretax if Category 2.C or below and 4% or less | Most recent trustee report on reporting date |
| Middle-market CLOs | Applicable adopted factor | No 11.77% surcharge | Most recent trustee report on reporting date |
The residual charge and thin-tranche surcharge are different treatments, not interchangeable rates. Use the trustee report available on the investment reporting date, not the tranche’s origination thickness.
What Should Buyers Know About Form A and Control?
A buyer reaching 10% of voting securities is presumed to acquire control under the NAIC model holding company act. That threshold applies to voting securities in a domestic insurer or its controlling company.
The buyer must file Form A and receive state approval before completing the acquisition. Control can also arise through contracts or other means of controlling influence, even without a 10% voting stake.
When an acquisition is presumed to involve control
Acquiring 10% or more of the voting securities creates a presumption of control under the model act. A regulator may also find control through contractual arrangements or other influence over the insurer.
Form A is an acquisition-of-control filing, not a substitute for other state filings. Buyers must follow the applicable state’s process for the proposed transaction.
What the Form A filing includes
The filing includes the acquirer’s audited financial statements for its most recent three fiscal years. If the acquirer has existed for fewer years, it submits statements for the years it has existed.
It also includes five-year projections for the insurer under the acquirer’s ownership. These materials help the regulator assess the planned ownership and the insurer’s expected course.
NAIC Form 12 serves a different filing purpose from Form A, so the numbers are not interchangeable. We should identify the required form using the current state instructions.
Do not close the acquisition before the relevant state insurance regulator has approved it.
Which Filings Apply When an Insurer Enters a State?
An insurer’s state entry begins with the licensing requirements of its proposed domicile, not with a single nationwide application rule. The intended lines also affect which filings and supporting papers apply.
The UCAA Form 1P is the primary state licensing application. Form 2F is a biographical affidavit used during the application process.
A UCAA license application does not replace the state’s own instructions for the proposed lines of authority.
Insurance filing requirements by state follow the insurer’s domicile and intended lines. A life insurer and a property/casualty insurer may face different application needs.
Before filing, check the state’s current checklist for:
- Required forms, including the applicable UCAA materials.
- Supporting financial documents.
- Lines of authority requested.
- Filing instructions and submission steps.
Confirm the current UCAA and state insurance department checklist before assembling the application.
Conclusion
A sound capital assessment starts with the insurer’s actual exposures and the rules that apply to its business. Capital adequacy depends on both the risks measured and the insurer’s line, domicile, and investments.
We should not treat one ratio or licensing threshold as a complete measure of solvency. The next practical step is to review the insurer’s latest RBC information and the requirements of its state regulator.
For a specific insurer, review its latest statutory filing alongside the current requirements of its domiciliary state.