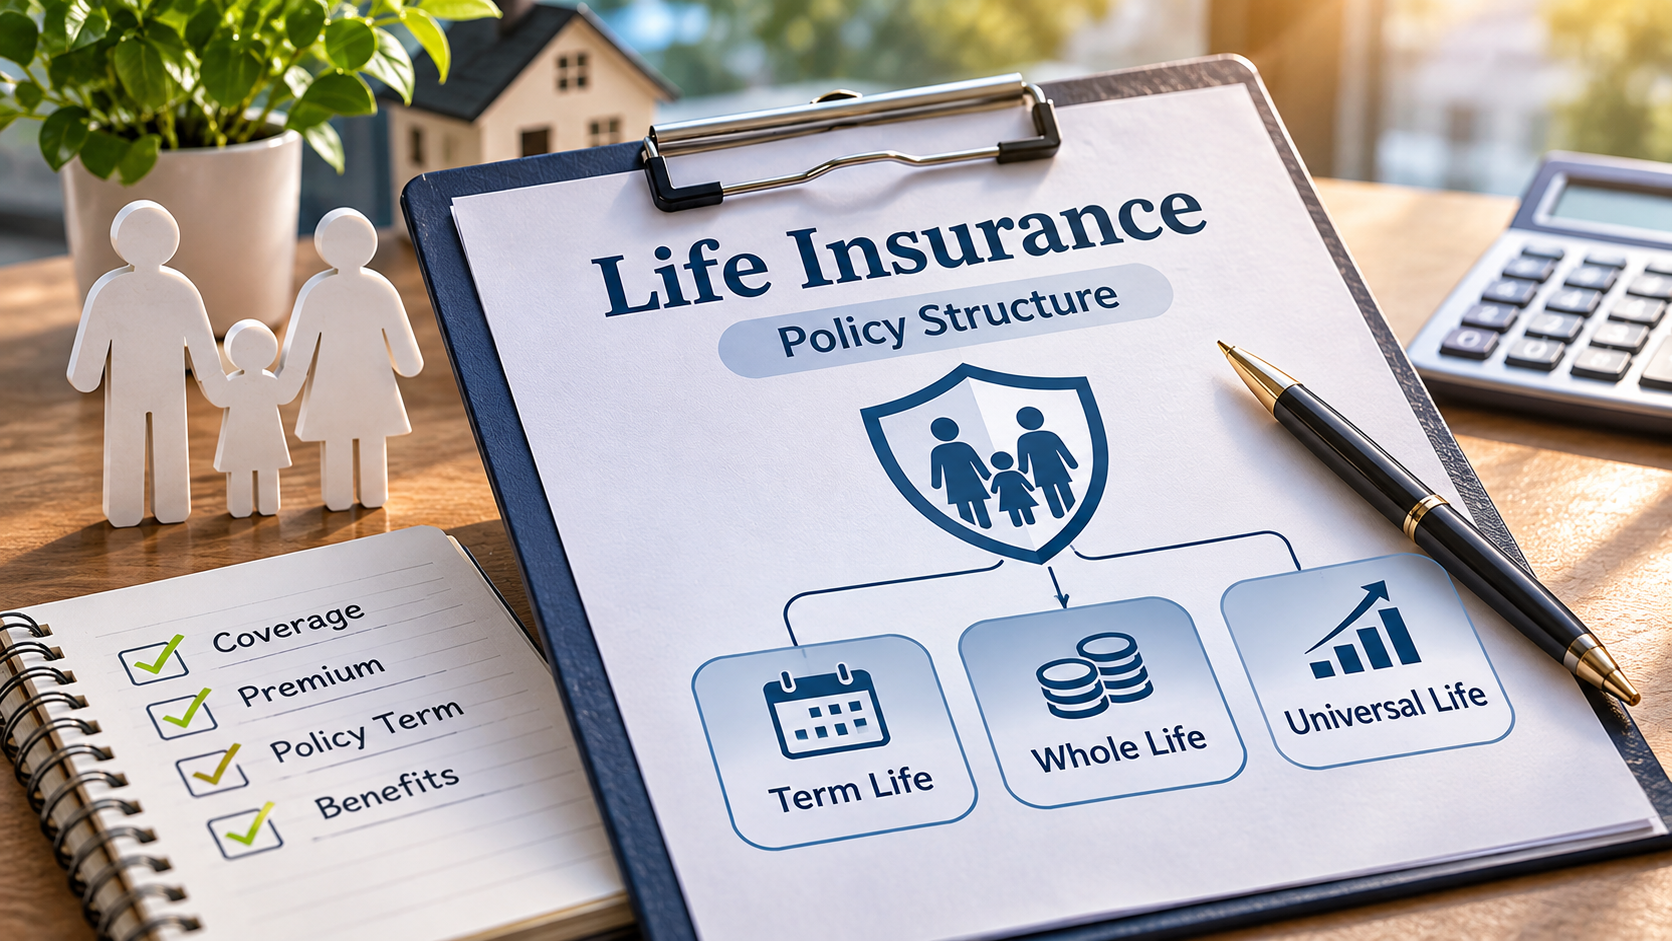
Life Insurance Policy Structures encompass a variety of options designed to protect your loved ones and meet your financial goals. From term insurance to whole and universal policies, understanding these structures is crucial for making informed decisions. This exploration will guide you through the nuances of each type, equipping you with the knowledge to choose the best policy for your needs.
As we dive deeper, you’ll discover how personal circumstances influence your choices, the impact of premiums on your budget, and the important role beneficiaries play. With insights into policy loans, cash value accumulation, and additional benefits, you’ll be well-prepared to navigate the life insurance landscape.
Understanding the Different Types of Life Insurance Policy Structures
Life insurance serves as a crucial financial safety net for individuals and their families. Understanding the various types of life insurance policies available can help you select the one that best meets your needs and financial goals. This guide highlights the primary categories of life insurance policies, namely term, whole, and universal life insurance, along with their features, advantages, drawbacks, and real-life applications.
Term Life Insurance
Term life insurance is designed to provide coverage for a specific period, typically ranging from 10 to 30 years. This type of policy pays a death benefit to the beneficiaries only if the insured passes away during the term. It is often considered the most straightforward form of life insurance.
Key features of term life insurance include:
- Affordability: Generally, term life premiums are lower compared to other types of policies, making it an attractive option for budget-conscious individuals.
- Fixed Coverage Period: The coverage lasts for a predetermined term, which can be chosen based on individual needs, such as paying off a mortgage or funding children’s education.
- No Cash Value: Unlike whole or universal life policies, term life does not accumulate cash value; it serves purely as protection during the specified term.
Real-life example: A 30-year-old purchasing a 20-year term policy for $500,000 may pay a monthly premium of around $25. If they pass away within those 20 years, their beneficiaries receive the full coverage amount. If they outlive the term, the policy expires without value.
Whole Life Insurance
Whole life insurance provides lifelong coverage and includes a savings component known as cash value. This policy remains in force as long as the premiums are paid, making it a long-term financial product.
The key features of whole life insurance include:
- Lifelong Coverage: Provides coverage for the insured’s entire life, ensuring a death benefit is paid no matter when they pass away.
- Cash Value Accumulation: A portion of the premium contributes to a cash value that grows at a guaranteed rate, which can be borrowed against or withdrawn.
- Higher Premiums: Whole life premiums are generally higher than term insurance due to the lifelong coverage and cash value benefits.
Real-life example: A 40-year-old buying a whole life policy for $250,000 may pay around $300 monthly. This policy not only provides a death benefit but also builds cash value that can be accessed during the policyholder’s lifetime.
Universal Life Insurance
Universal life insurance is a flexible form of permanent life insurance that combines a death benefit with a cash value component. It offers the ability to adjust premiums and death benefits as financial situations change.
Notable features of universal life insurance include:
- Flexible Premiums: Policyholders can vary their premium payments, allowing them to adjust contributions based on their financial circumstances.
- Adjustable Death Benefit: The death benefit can be adjusted, providing policyholders with the option to increase or decrease coverage as needed.
- Interest Earnings: The cash value grows based on current interest rates, which can vary, providing potential for growth but also introducing risk.
Real-life example: A 35-year-old may choose a universal life policy with a $1 million death benefit and contribute $400 monthly. If they need to lower their premiums due to financial constraints, they can adjust their payments while maintaining coverage.
The Importance of Policy Structure in Life Insurance Selection
Choosing the right life insurance policy structure is essential for ensuring that you and your loved ones are adequately protected financially. The policy structure you select can significantly impact your financial security and the benefits available to your beneficiaries. Understanding the importance of the policy structure allows individuals to make informed decisions tailored to their personal and financial situations.
Several factors influence an individual’s choice of life insurance policy structure. Critical elements include personal circumstances such as age, health, and financial situation. Each of these factors plays a crucial role in determining which policy structure may be most appropriate for an individual.
Influential Factors in Policy Structure Selection
Personal circumstances can drastically shape the decision-making process. Below are key factors that individuals should consider when selecting a life insurance policy structure:
- Age: Younger individuals may prefer term life insurance for its lower premiums, while older individuals might opt for whole life insurance for the lifelong coverage it provides.
- Health: Pre-existing health conditions can affect premium costs and eligibility for certain types of policies. A healthier individual may qualify for better rates compared to someone with significant health issues.
- Financial Situation: Individuals should evaluate their current financial status and future goals. Those looking for investment opportunities may lean towards permanent policies, while those seeking affordable coverage might choose term policies.
Long-term implications of selecting one policy structure over another can be significant. For instance, choosing a term life policy may result in lower initial costs, but it can also lead to the need for renewal or conversion later in life, potentially at higher rates due to age or health changes. On the other hand, a whole life policy offers lifelong coverage and builds cash value, which can be borrowed against or withdrawn, providing financial flexibility.
“Selecting the right life insurance policy structure is a vital step in securing your financial future and protecting your loved ones.”
How Premiums are Affected by Different Policy Structures
The cost of premiums in life insurance policies is intricately tied to the structure of the policy itself. Understanding this relationship is essential for consumers looking to manage their budget while securing adequate coverage. Premiums are calculated based on various factors, including the type of policy, the coverage amount, the insured’s age, health status, and the policy’s features.
The type of life insurance policy chosen can significantly impact the premium costs, primarily categorized into two types: fixed and variable premiums. Fixed premiums remain constant throughout the policy’s lifespan, offering predictability and ease of budgeting for policyholders. In contrast, variable premiums can fluctuate based on the performance of underlying investments or other factors, adding a layer of complexity to premium management.
Comparison of Fixed and Variable Premiums
The distinction between fixed and variable premiums is crucial for individuals considering life insurance. Fixed premiums provide stability, while variable premiums offer potential for growth or savings based on investment performance. Below are key points highlighting this comparison:
- Fixed Premiums: These premiums remain unchanged regardless of market conditions, making it easier for policyholders to forecast their insurance costs over time.
- Variable Premiums: These can change based on investment performance and other factors, potentially leading to lower initial costs but increased financial risk.
- Example of Fixed Premiums: A whole life insurance policy typically has fixed premiums that are established at the time of purchase and remain the same throughout the contract.
- Example of Variable Premiums: A universal life policy may allow policyholders to adjust their premiums and coverage amounts, often leading to fluctuating costs based on cash value performance.
The payment schedules for premiums can also vary significantly depending on the selected policy structure. Many policies offer flexible payment options, which can affect overall cost and accessibility.
Premium Payment Schedules and Policy Structures
Understanding the different premium payment schedules can help policyholders choose a plan that aligns with their financial capabilities. Payment options vary based on the policy type and provider. Below are common payment schedules:
- Annual Payments: Policyholders pay the total premium once a year, often resulting in lower overall costs due to fewer administrative fees.
- Semi-Annual Payments: Premiums are paid every six months, which can be easier to manage for those who may struggle with a large one-time payment.
- Quarterly Payments: This option divides the premium into four payments, providing more frequent opportunities to manage cash flow.
- Monthly Payments: Monthly installments are often the most flexible but can lead to higher total costs over time due to more frequent transactions.
In summary, the relationship between life insurance policy structures and premium costs is multifaceted. Consumers should carefully evaluate their options, considering fixed versus variable premiums and the implications of different payment schedules. This understanding will empower them to make informed decisions that best suit their financial situation and insurance needs.
The Role of Beneficiaries in Various Life Insurance Policy Structures
Naming beneficiaries is a crucial aspect of life insurance policies, as it determines who will receive the policy’s death benefit upon the insured’s passing. The designation of beneficiaries can significantly impact the payout process, ensuring that the intended individuals are provided for according to the policyholder’s wishes. The importance of selecting beneficiaries varies across different types of life insurance policies, influencing the overall structure and benefits provided.
Understanding the legal considerations surrounding beneficiary designations is essential for policyholders. Each life insurance policy type may have distinct rules or implications regarding how beneficiaries are named and the consequences of those choices. This includes factors such as whether a beneficiary can be changed, the rights of contingent beneficiaries, and the tax implications associated with the payout. For example, policies with irrevocable beneficiaries require the policyholder to obtain consent for any changes, while revocable designations allow for greater flexibility.
Impact of Beneficiary Choices on Payout Process
The selection of beneficiaries can directly affect the efficiency and speed of the claims process. Here are several key points to consider regarding how beneficiary choices influence payouts:
- Primary vs. Contingent Beneficiaries: Primary beneficiaries are the first in line to receive benefits, while contingent beneficiaries only receive the benefits if the primary beneficiaries are deceased or unable to claim. Properly naming both ensures a smooth claim process.
- Types of Beneficiaries: Individuals, entities, or trusts can be named as beneficiaries. Each choice carries different implications, such as tax consequences or the need for legal guidance in case of complex trusts.
- Legal Designations: In some cases, legal or marital designations may affect beneficiary status. For instance, a spouse may have rights over the benefits regardless of the policyholder’s wishes, depending on state laws.
- Impact of Divorce or Separation: Failing to update beneficiary designations after a marital change can lead to unintended payouts. For example, an ex-spouse may receive policy benefits unless formally changed.
- Minors as Beneficiaries: Naming minors can complicate payout processes since insurance companies may require a guardian to manage the funds, potentially delaying access to the benefits.
“The designation of beneficiaries is not just a legal formality; it is a vital component in ensuring that your loved ones are protected and provided for according to your wishes.”
Real-life examples illustrate these points well. For instance, a policyholder who named their adult child as the primary beneficiary while also identifying their spouse as a contingent beneficiary may face complications if the adult child predeceases them. In this scenario, the spouse would automatically become the primary beneficiary, but if the policyholder fails to update the beneficiary designation, the payout could create conflicts or legal disputes. Another example involves naming a trust as a beneficiary, which can provide asset protection and control over how the funds are distributed, but may require additional administrative steps to ensure compliance with legal requirements.
In summary, the role of beneficiaries in life insurance policies is significant and multifaceted, influencing not only the distribution of benefits but also the legal and procedural aspects that accompany such designations. By understanding these dynamics, policyholders can make informed decisions that align with their estate planning goals and familial needs.
Policy Loans and Cash Value Accumulation in Life Insurance
Life insurance is often viewed as a financial safety net, but certain policy structures also offer an interesting feature: cash value accumulation. Whole and universal life insurance policies not only provide a death benefit but also build cash value over time, allowing policyholders to access funds during their lifetime. Understanding how these features work is essential for making informed decisions about your financial future.
Whole life and universal life policies are designed to accumulate cash value, which can be accessed or borrowed against. Whole life insurance offers a fixed premium and guaranteed cash value growth, while universal life insurance provides more flexibility in premium payments and growth potential based on market performance. Over time, the cash value in these policies can grow significantly, providing a financial resource for various needs.
Policy Loan Process and Effects
Taking out a policy loan is a straightforward process, but it is important to understand its implications. When a policyholder borrows against the cash value, they are essentially taking a loan from the insurance company, using their own policy as collateral. The amount available for borrowing is typically a percentage of the cash value, and interest is charged on the loan amount.
It is crucial to note that any outstanding loans and interest will reduce the death benefit. If the loan is not repaid, the remaining cash value will be used to settle the loan balance upon the policyholder’s death. This can significantly impact the financial security intended for beneficiaries. Therefore, careful consideration should be given before tapping into the cash value.
Benefits and Risks of Cash Value Access
Accessing cash value can provide several advantages, but it also comes with risks. Below are the key points to consider:
- Benefits:
- Immediate access to funds for emergencies, education, or investments.
- Loan amounts can be lower than traditional loans due to the collateral backing.
- No credit check is required, making it easier to access funds.
- Risks:
- Outstanding loans reduce the death benefit, impacting beneficiaries.
- Interest accumulation can erode the cash value if not managed properly.
- If the policy lapses due to unpaid loans, the policyholder could lose their insurance coverage.
A well-considered approach to policy loans and cash value accumulation can enhance financial flexibility, but policyholders should weigh the benefits against the potential risks. Decision-making should involve careful assessment of individual circumstances and future needs.
The Impact of Policy Structure on Riders and Additional Benefits
The structure of a life insurance policy plays a crucial role in determining the options available for riders and additional benefits. Riders are supplemental provisions that enhance the coverage of the main insurance policy, offering customized protection depending on individual needs. Understanding how policy structure can influence these options is essential for making informed decisions.
Riders are typically added to the base life insurance policy to provide additional coverage or benefits without needing a separate policy. They can significantly enhance the overall protection offered by the insurance plan. Commonly available riders include:
Common Riders Available for Life Insurance Policies
These riders serve different purposes and can be tailored based on personal circumstances. The following list Artikels some popular riders and their key features:
- Accidental Death Benefit Rider: This rider provides an additional payout if the insured dies due to an accident, increasing the total death benefit significantly.
- Critical Illness Rider: This rider offers a lump-sum payout upon diagnosis of a covered critical illness, aiding in medical expenses and recovery costs.
- Waiver of Premium Rider: If the policyholder becomes disabled and unable to pay premiums, this rider allows for premium payments to be waived while keeping the policy active.
- Children’s Rider: This rider provides coverage for the policyholder’s children, ensuring financial protection in case of an unfortunate event.
- Long-Term Care Rider: It allows policyholders to access their death benefit to cover long-term care expenses, alleviating financial burdens during extended illnesses.
The flexibility and availability of these riders can vary significantly depending on the life insurance policy’s structure.
Impact of Policy Structure on Options for Additional Benefits
The policy structure can either expand or limit the options available for riders and additional benefits. Most importantly, the type of policy—whether it’s term, whole, or universal life—will dictate the extent of customization possible.
For instance, whole life policies often offer more rider options compared to term life policies, which may restrict additional benefits. This limitation can be attributed to the inherently different nature of these policies. Whole life policies, with their cash value component, can afford to incorporate riders that enhance value over time without compromising the core protection offered.
“Whole life insurance policies generally allow for a wider range of riders due to their cash value feature, which provides more financial flexibility.”
Furthermore, certain insurance companies may have their own policies regarding riders, which can further influence what can be added based on the existing policy structure.
Costs Associated with Adding Riders
While riders enhance life insurance policies, they often come with additional costs. This expense can vary significantly depending on the type of rider and the base policy structure. Understanding these costs is essential for evaluating the financial implications of adding riders to a policy.
The cost structure of riders typically includes:
- Base Premium Increase: Adding a rider will usually result in an increase in the overall premium, reflecting the additional coverage.
- Age and Health Factors: The policyholder’s age and health status can affect rider costs, with older applicants or those with pre-existing conditions facing higher premiums.
- Type of Rider: Different riders have different pricing structures; for instance, critical illness riders might be more expensive than accidental death riders due to the higher risk involved.
Ultimately, assessing the costs versus the benefits of riders in relation to the chosen policy structure is a critical step in ensuring optimal coverage suited to individual needs.
How to Evaluate Life Insurance Policy Structures for Family Needs
Evaluating life insurance policy structures for a family requires a thoughtful approach that considers various factors. Understanding the unique needs and circumstances of your family can guide you towards selecting a policy that provides adequate coverage and benefits. This evaluation framework will help families navigate their options and make informed decisions regarding life insurance.
Assessing the right life insurance policy structure involves a comprehensive analysis of financial goals, dependents, and future obligations. It’s essential to account for both current and projected family needs when choosing a policy, as these factors can significantly influence what type of coverage is most appropriate.
Key Factors for Evaluation
When evaluating life insurance policy structures, several critical factors should be considered to ensure that the selected policy aligns with family needs. The following points Artikel these considerations:
- Financial Goals: Define your family’s financial objectives, such as funding education, paying off debts, or maintaining a certain lifestyle. Understanding these goals will help you determine the necessary coverage amount.
- Dependents: Assess the number and age of dependents. For families with young children, larger coverage may be necessary to secure their future until they become financially independent.
- Future Obligations: Consider any looming financial responsibilities, such as mortgages or educational expenses. These obligations should be factored into the policy amount to ensure adequate coverage.
- Current Income: Evaluate your family’s current income and how it would impact the coverage needed. A policy should ideally replace lost income to maintain the family’s standard of living.
- Health Conditions: Take into account any existing health conditions among family members that may influence the type and cost of coverage. This includes both the insured person’s health and any dependents.
- Policy Flexibility: Look for policies that offer adjustability in coverage amounts or premium payments to accommodate changing family needs over time.
Considering these factors allows for a tailored approach when selecting a life insurance policy, ensuring that the chosen structure meets the evolving needs of the family.
“Evaluating your life insurance needs is a dynamic process that should evolve alongside your family’s circumstances.”
Incorporating these elements into your decision-making process will facilitate informed choices that align well with both current and future family dynamics.
The Future of Life Insurance Policy Structures in a Changing Economy
The landscape of life insurance policy structures is undergoing significant transformation in response to economic fluctuations and technological advancements. As individuals navigate an increasingly dynamic financial environment, the demand for more flexible and innovative insurance solutions is on the rise. This shift not only reflects consumer preferences but also highlights the critical need for insurers to adapt their offerings to meet emerging challenges and opportunities.
Economic changes, such as inflation, interest rates, and shifts in consumer behavior, are influencing the design and attractiveness of life insurance products. Insurers are now reevaluating traditional models to incorporate features that align with contemporary needs. The evolution of policy structures is being propelled by various factors, including the increasing demand for transparency and customization in insurance offerings.
The Influence of Technology on Policy Offerings
Technology plays a pivotal role in shaping the future of life insurance policy structures. Innovations such as artificial intelligence, machine learning, and big data analytics are being leveraged to enhance underwriting processes, tailor policy features, and improve customer engagement.
The integration of digital tools allows for quicker policy issuance and more personalized customer experiences. For example, digital platforms enable policyholders to manage their accounts, make claims, and access resources with unprecedented ease. Automated underwriting systems process vast amounts of data to evaluate risk more accurately, which can lead to more competitive pricing and broader access to coverage.
Moreover, the emergence of insurtech companies is disrupting traditional insurance models. These startups often focus on niche markets, offering unique products like usage-based life insurance that cater to specific consumer needs. This trend signifies a shift in how policies are structured and marketed, making them more adaptable to individual circumstances.
Trends in Hybrid Products and Their Impact
The introduction of hybrid products is reshaping the framework of traditional life insurance policies. These innovative offerings, which combine elements of life insurance and investment components, appeal to a broader audience by addressing various financial goals within a single product.
Hybrid products, such as life insurance with long-term care benefits or investment-linked policies, provide policyholders with greater flexibility and value. These products are particularly attractive in a landscape where consumers prioritize comprehensive financial solutions that address both protection and growth.
The potential impact of hybrid products on traditional policy frameworks is significant. They challenge the conventional notion of life insurance as a purely protective tool, transforming it into a versatile financial asset. As consumers increasingly seek products that offer a blend of risk coverage and investment growth, traditional insurers must evolve to compete with these innovative solutions.
In summary, the future of life insurance policy structures is being reshaped by economic changes and technological advancements. The evolution towards more flexible, consumer-focused offerings is essential for insurers to remain relevant in a rapidly changing financial landscape.
Outcome Summary
In summary, Life Insurance Policy Structures offer varied pathways to secure your family’s financial future. As you consider the implications of each structure, remember that your unique circumstances will guide your choices. Embracing this knowledge will not only help you select the right policy but also empower you to adapt to future changes in your life and the economy.
Essential FAQs
What is the difference between term and whole life insurance?
Term insurance provides coverage for a specific period, while whole life insurance offers lifelong coverage with a cash value component.
Can I change my life insurance policy structure later?
Yes, many insurers allow policyholders to convert term policies to permanent ones or adjust their coverage, but this may depend on the terms of the policy.
What factors should I consider when choosing a beneficiary?
Consider their financial needs and relationship to you, as well as any legal implications and potential tax consequences.
How do I access the cash value in my whole life policy?
You can borrow against the cash value or withdraw funds, but it’s important to understand the implications on your death benefit.
Are riders worth adding to my life insurance policy?
Riders can provide additional benefits tailored to your needs, making them worth considering, but evaluate their costs against the coverage they offer.