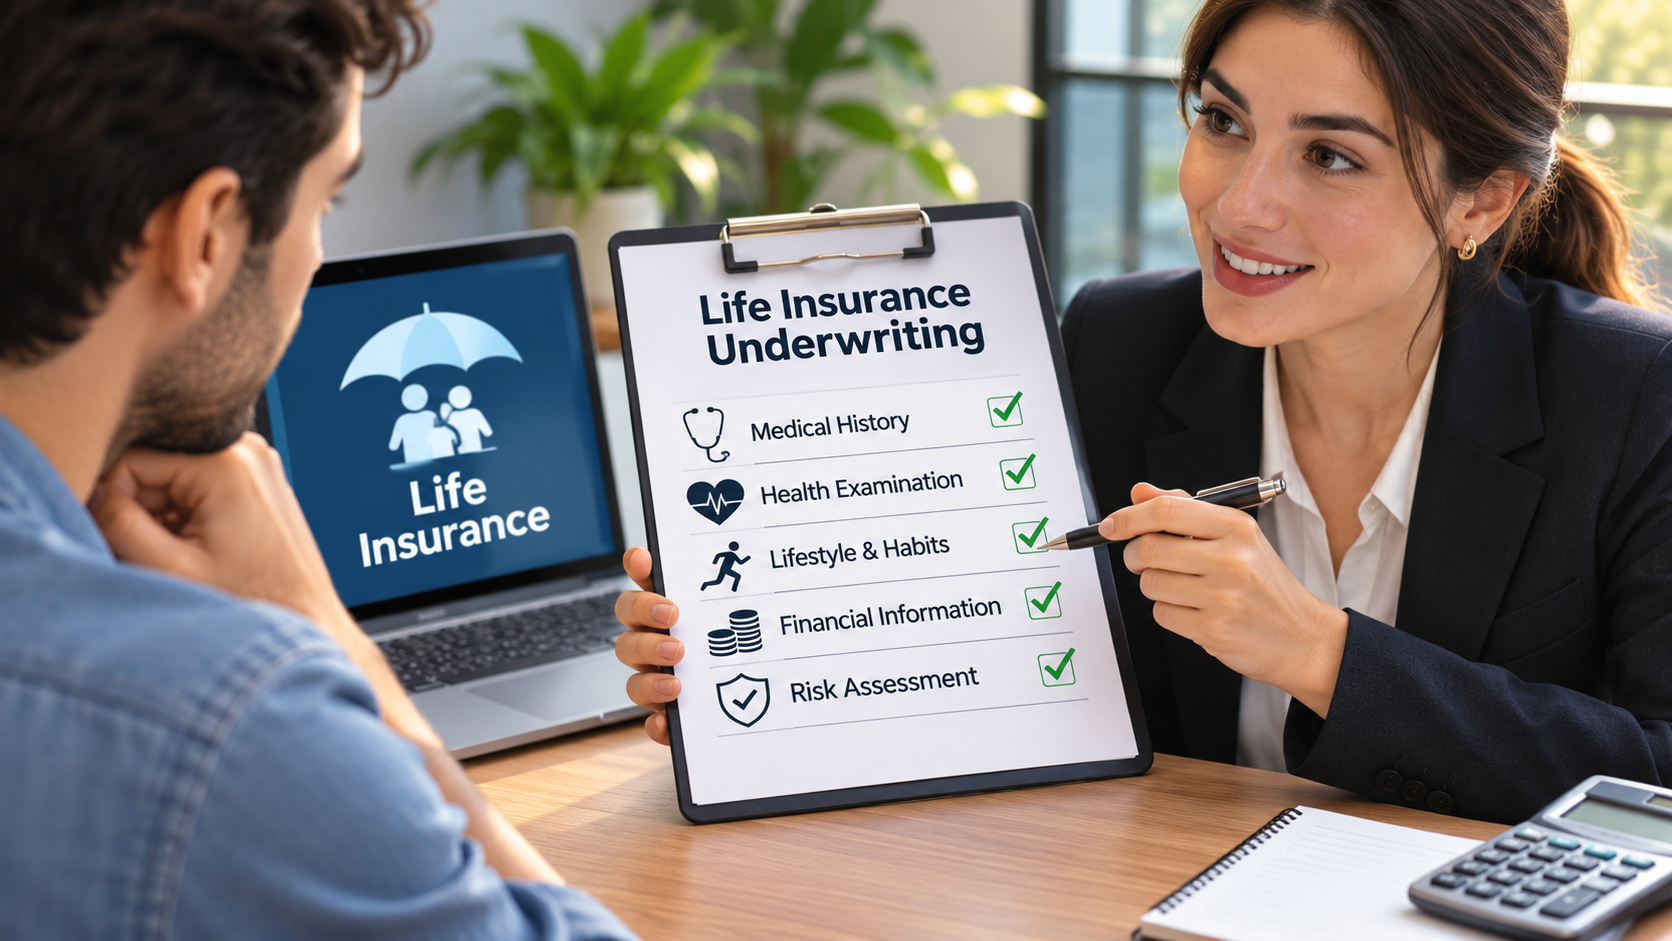
Life Insurance Underwriting Requirements are essential for anyone looking to secure a policy. They serve as the benchmark for assessing an applicant’s eligibility and determining premiums, making them a critical aspect of the life insurance process. By understanding these requirements, potential policyholders can navigate the insurance landscape with more confidence and clarity.
The underwriting process involves evaluating various factors, including age, health, lifestyle, and even technology use. This ensures that insurers can accurately assess risk and provide tailored coverage options for applicants. In doing so, the requirements help establish a fair balance between the insurer’s financial stability and the applicant’s needs.
Understanding the Concept of Life Insurance Underwriting Requirements
Life insurance underwriting requirements play a crucial role in the insurance industry by establishing the criteria that insurance companies use to evaluate risks associated with applicants. This process is essential for ensuring that policies are issued fairly and that premiums are set accurately. In essence, underwriting helps insurers decide who they will cover and under what terms, thereby protecting both the insurer and the insured from financial loss.
The fundamental principles of life insurance underwriting revolve around risk assessment, which is the evaluation of the likelihood that a policyholder will make a claim. Underwriters analyze various factors, including the applicant’s health history, lifestyle choices, and occupation, to assess potential risks. The significance of these requirements lies in their ability to inform the underwriting decision, ensuring that the insurer can maintain a sustainable business model while providing essential coverage to individuals.
Key Terms Associated with Life Insurance Underwriting
Understanding specific terminology related to life insurance underwriting is vital for grasping its principles. Here are some key terms:
- Underwriting: The process of evaluating risk and determining the terms of insurance coverage.
- Risk Assessment: The evaluation process that assesses the likelihood of a policyholder making a claim.
- Premium: The amount paid by the policyholder for insurance coverage.
- Morbidity: The rate of disease or illness within a specific population, which impacts underwriting decisions.
- Mortality Rate: The frequency of death in a certain population, influencing life insurance pricing.
The role of underwriting in assessing risk is pivotal. Underwriters gather data through various methods, including medical exams and questionnaires, to create a comprehensive profile of the applicant. This profile enables them to predict the probability of a claim being made. Based on this risk analysis, underwriters determine appropriate premium rates, ensuring that they align with the level of risk presented by the applicant.
“Underwriting is not just about mitigating risk; it’s about understanding the unique circumstances of each individual.”
For example, an applicant who is a non-smoker in excellent health is typically viewed as a lower risk compared to someone with chronic health conditions or a history of hazardous occupations. This detailed underwriting process ultimately helps insurance companies maintain financial stability while providing necessary coverage for policyholders.
Identifying Common Underwriting Criteria for Life Insurance
The underwriting process is essential for life insurance companies to assess the risk of insuring an applicant. By evaluating certain criteria, insurers determine not only eligibility but also premium rates and coverage limits. Understanding these criteria can help prospective policyholders prepare for the application process.
Insurers commonly consider several factors that play a significant role in evaluating an applicant’s risk profile. These criteria include age, health status, occupation, and lifestyle choices. Each of these elements can substantially impact the underwriting process and the final decision regarding coverage.
Common Underwriting Criteria
The following points Artikel the key underwriting criteria used by life insurance companies:
- Age: Generally, younger applicants are viewed as lower risk, resulting in lower premiums. As age increases, the likelihood of health issues also rises, which may lead to higher premiums or even denial of coverage.
- Health Status: Insurers assess an applicant’s overall health, including pre-existing conditions, medical history, and current medications. For instance, someone with a chronic illness like diabetes may face higher premiums, while those in excellent health may qualify for preferred rates.
- Occupation: Certain professions carry higher risks than others. For example, individuals in high-risk jobs, such as construction workers or pilots, may experience stricter underwriting standards and potentially higher premiums compared to those in less hazardous occupations, like office workers.
- Lifestyle Choices: Factors such as smoking, alcohol consumption, and participation in risky activities (e.g., extreme sports) can adversely affect an applicant’s risk evaluation. A smoker, for instance, typically pays higher premiums due to the associated health risks.
The interplay of these factors can significantly alter an applicant’s eligibility for coverage. For example, a 25-year-old non-smoker in great health is likely to receive more favorable terms compared to a 50-year-old smoker with a history of heart disease. Insurers utilize these underwriting criteria to manage their risk while providing coverage that aligns with the applicant’s profile.
The underwriting decision is not just about assessing risk; it’s also about pricing the policy correctly based on the applicant’s unique circumstances.
The Role of Medical Exams in Life Insurance Underwriting
Medical exams play a crucial role in the life insurance underwriting process, providing insurers with vital insights into an applicant’s health status. These evaluations help determine the risk associated with insuring an individual and influence the terms and premiums of the policy. A comprehensive medical assessment allows underwriters to make informed decisions, ensuring that both the insurance company and the policyholder are adequately protected.
Insurers typically require various medical exams as part of the underwriting process. These exams can vary based on the applicant’s age, the amount of coverage sought, and specific health concerns. Insurers look for critical health indicators during these evaluations, which include:
Types of Medical Exams and Evaluations
Medical exams may include a combination of physical examinations, blood tests, and health questionnaires. The following are commonly required components of a medical exam:
- Physical Examination: A general health check-up conducted by a licensed healthcare provider, assessing vital signs such as blood pressure, heart rate, and overall physical condition.
- Blood Tests: Laboratory tests that analyze blood samples for cholesterol levels, glucose levels, and markers for various diseases, such as diabetes or high cholesterol.
- Urinalysis: A test of urine samples, providing information about kidney function and detecting signs of potential health issues, such as diabetes or infections.
- Health Questionnaire: A detailed form filled out by the applicant, capturing personal and family medical histories, lifestyle habits, and any pre-existing conditions.
During these evaluations, insurers specifically look for several key factors that can indicate the applicant’s overall health risk.
Understanding health conditions, family history, and lifestyle choices is essential for accurate risk assessment.
Potential outcomes of medical exams can significantly impact an applicant’s insurance journey. Depending on the findings, applicants may experience various implications:
- Approval: If the exam results indicate good health, the applicant is likely to receive approval for coverage at favorable rates.
- Rate Adjustment: Results may lead to higher premiums if health concerns are identified, reflecting the increased risk taken on by the insurer.
- Decline of Coverage: In cases of severe health issues or high-risk factors, insurers may decline coverage altogether, leaving applicants with limited options.
In summary, medical exams are integral to the life insurance underwriting process, providing critical health information that influences coverage decisions. By comprehensively assessing an applicant’s medical status, insurers can effectively manage risk while offering tailored policies to meet individual needs.
Comparing Underwriting Processes Among Different Insurance Companies
The underwriting process is a critical component of life insurance that determines who qualifies for coverage and at what price. Different insurance companies adopt varying underwriting practices, which can significantly influence policy pricing and approval rates. Understanding these differences can help consumers make informed choices when selecting a life insurance provider.
The underwriting processes employed by life insurance companies can vary widely, impacting the overall effectiveness and efficiency of the policy acquisition experience. Various companies may prioritize different factors, such as health history, lifestyle choices, and medical examinations, which can lead to diverse outcomes in terms of coverage options and pricing for applicants.
Key Differences in Underwriting Processes
When comparing underwriting processes, it’s essential to consider several critical aspects that can influence the consumer’s experience and policy outcomes. Below is an analysis of various practices among leading life insurance companies:
- Health Assessments: Some insurers require comprehensive medical exams, while others may rely on health questionnaires and existing medical records. For instance, companies like MetLife may favor a full medical exam for higher coverage amounts, whereas companies like Haven Life utilize accelerated underwriting models that expedite the process without extensive exams.
- Lifestyle Considerations: Insurers assess lifestyle factors such as smoking, alcohol use, and physical activity levels differently. For example, a smoker may face higher premiums with companies like Prudential, while others like State Farm might offer programs to help policyholders quit and subsequently reduce premiums.
- Age and Gender Factors: Some companies adjust pricing models based on age and gender more aggressively than others. For instance, AIG may have a more stringent age-related pricing model, while Transamerica could offer competitive rates for older applicants.
- Technology Use: The level of technology integration in underwriting processes can vary. Companies that leverage big data and AI, such as Lemonade, tend to provide faster approvals and more personalized pricing, whereas traditional insurers may have slower, more manual processes.
- Medical History Review: The depth of medical history examination influences the speed of underwriting. For example, companies like Northwestern Mutual may conduct extensive reviews of medical records, while others may only request significant health information from the past five years.
Understanding these differences is vital for consumers when selecting an insurance provider based on their personal health situations and lifestyle choices. It’s essential to evaluate the specific underwriting practices of different companies as they can lead to varying approval rates and premium costs.
“A thorough understanding of underwriting processes can often yield significant savings and more tailored coverage options for consumers.”
When evaluating life insurance options, consumers should consider not only the immediate costs but also the long-term implications of underwriting practices on their coverage. By analyzing these differences, individuals can better navigate their choices in a way that aligns with their unique health profiles and financial goals.
Understanding the Impact of Pre-existing Conditions on Underwriting
Pre-existing medical conditions can significantly influence life insurance underwriting decisions. Underwriters assess the risk associated with these conditions to determine eligibility, coverage options, and premiums. Understanding the implications of such health issues is crucial for applicants seeking to secure life insurance.
Insurance companies categorize pre-existing conditions based on their severity, manageability, and potential impact on mortality. Commonly classified conditions include diabetes, heart disease, cancer, and mental health disorders. Each condition is evaluated on a range of factors, including its type, treatment history, and current management status. This categorization directly affects available coverage options and premium calculations.
Categories and Effects of Specific Conditions
The categorization of pre-existing conditions plays a vital role in determining underwriting outcomes. Here’s a closer look at how different types of conditions can affect life insurance coverage:
- Diabetes: Applicants with well-managed diabetes may receive favorable terms, while uncontrolled diabetes can lead to higher premiums or even denial of coverage.
- Heart Disease: Individuals with a history of heart disease face more scrutiny. Underwriters assess factors like age at diagnosis and treatment effectiveness.
- Cancer: The type of cancer, stage at diagnosis, and time since treatment completion influence underwriting. Those in remission may secure better rates than those currently undergoing treatment.
- Mental Health Disorders: Conditions such as depression or anxiety can be evaluated based on treatment history and recurrence, impacting both rates and coverage options.
Understanding these categories can help applicants anticipate potential challenges in the underwriting process.
Strategies for Improving Coverage Chances
Applicants with pre-existing conditions can take proactive steps to enhance their chances of obtaining life insurance coverage. Here are some effective strategies:
- Thorough Documentation: Providing complete medical records and treatment history creates transparency and may lead to more favorable underwriting decisions.
- Consultation with Healthcare Providers: Regular check-ups and a solid treatment plan signal to insurers that the condition is well managed, which can positively influence premium rates.
- Timing of Application: Waiting to apply until a condition is under control or in remission can yield better insurance terms and premium rates.
- Shopping Around: Different insurers have varying underwriting guidelines. Comparing offers can help find a policy that aligns with an individual’s health status.
By employing these strategies, applicants can navigate the complexities of life insurance underwriting more effectively, potentially securing coverage that reflects their current health status.
Exploring the Role of Non-Medical Factors in Underwriting Decisions
When it comes to life insurance underwriting, medical history often takes center stage. However, non-medical factors also play a significant role in the underwriting process. These elements can influence the risk assessment and ultimately the premiums that applicants may face. Understanding these factors helps provide a more holistic view of an individual’s risk profile.
Non-medical factors, such as hobbies, travel habits, and family medical history, can heavily influence underwriting outcomes. Insurers evaluate these elements to determine potential risks that may not be immediately evident through medical records alone. For instance, an applicant who participates in extreme sports like skydiving or rock climbing may be seen as higher risk than someone with a more sedentary lifestyle. Similarly, frequent international travel to regions with prevalent health concerns could raise flags during the underwriting process.
Impact of Unique Lifestyle Choices on Risk Assessment
Certain lifestyle choices can significantly alter an applicant’s risk profile. Below are some examples illustrating how these choices might impact underwriting decisions:
- Hobbies: Engaging in high-risk activities such as scuba diving or motorcycle racing can increase the likelihood of accidents, leading insurers to adjust premiums accordingly.
- Travel Habits: Regular travel to countries with high rates of infectious diseases or political instability may be deemed high risk. An applicant who frequently travels to such regions may face higher premiums or additional scrutiny during underwriting.
- Family Medical History: A family history of serious illnesses like heart disease or cancer can also affect underwriting decisions. If an applicant has immediate family members who have faced these conditions, insurers may perceive them as a higher risk.
Honesty in disclosing non-medical factors during the application process is crucial. Providing accurate information allows insurers to make informed decisions and offer fair assessments.
Failure to disclose relevant details can lead to complications in claims processing or even policy cancellation.
It’s vital to remember that full transparency can ultimately benefit both the applicant and the insurer, fostering a relationship built on trust and understanding.
The Influence of Technology on Life Insurance Underwriting
Advancements in technology are reshaping the life insurance underwriting process, making it more efficient and accurate. As the industry continues to adopt new tools and methodologies, traditional underwriting practices are evolving to meet modern demands. This transformation is driven primarily by data analytics and artificial intelligence, which streamline operations while enhancing decision-making.
The integration of technology in underwriting practices has led to significant changes in how insurers assess risk and determine premiums. By leveraging data analytics, underwriters can analyze vast amounts of information quickly, allowing for more precise evaluations. This shift not only accelerates the underwriting process but also improves the customer experience by providing faster decisions and greater personalization.
Data Analytics and Artificial Intelligence in Underwriting
The implementation of data analytics and AI in life insurance underwriting has the potential to revolutionize the industry. These technologies enable insurers to gather and process data from various sources, including medical records, lifestyle factors, and even social media activity. Here are some important aspects illustrating their impact:
– Risk Assessment Improvements: Advanced algorithms can predict risk more accurately by analyzing patterns in historical data. Insurers can use these insights to refine their underwriting criteria and improve risk segmentation.
– Streamlined Processes: Automation of repetitive tasks allows underwriters to focus on complex cases, resulting in faster processing times. For instance, automated systems can handle preliminary data collection and flag anomalies for human review.
– Personalized Premium Pricing: AI can create tailored insurance products by considering individual risk factors, leading to more competitive pricing models. This customization fosters a better match between coverage and individual needs.
– Enhanced Claims Management: By analyzing claims data, insurers can identify trends and commonalities that may highlight areas for risk mitigation or product development.
While technology presents numerous advantages, it also introduces challenges that must be addressed to fully harness its potential. These challenges include:
– Data Privacy Concerns: The collection and use of personal data raise significant privacy issues. Insurers must ensure compliance with regulations and ethical standards to protect consumer information.
– Dependence on Technology: Over-reliance on automated systems can lead to vulnerabilities, especially if algorithms are not regularly updated or audited for accuracy. Insurers need to maintain a balance between technology and human judgment.
– Integration Costs: Implementing cutting-edge technology often requires substantial investment and training for existing staff. Smaller insurers may struggle to adopt these advancements due to resource limitations.
In summary, the fusion of technology with life insurance underwriting is an ongoing journey, presenting both opportunities and hurdles. By effectively utilizing data analytics and AI, the industry can enhance its operational efficiencies, improve risk assessment accuracy, and ultimately provide customers with personalized insurance solutions.
Understanding the Appeal Process for Underwriting Decisions
Navigating the life insurance underwriting process can be challenging, especially when an application for coverage is denied. It’s important to know that applicants have the right to appeal these decisions. Understanding the appeal process provides applicants with a means to contest unfavorable outcomes and potentially secure the life insurance coverage they need.
The appeal process for underwriting decisions involves several steps that allow the applicant to present their case for reconsideration. After receiving a denial notice, applicants should carefully review the reasons for the denial. This information typically Artikels the specific underwriting criteria that were not met. Knowing these details is crucial as they form the basis for the appeal. To initiate the appeal process, applicants need to follow a structured approach that may vary depending on the insurance provider.
Steps and Documentation Required to Initiate an Appeal
To effectively initiate an appeal, it is important to gather the necessary documentation and follow a clear process. Here are the essential steps:
1. Review the Denial Letter: Understand the reasons for denial and gather relevant information.
2. Collect Supporting Documents: Include medical records, additional information that addresses the underwriting concerns, or statements from health professionals.
3. Draft an Appeal Letter: Clearly articulate the reasons for the appeal, referencing the denial letter and the supporting documents.
4. Submit the Appeal: Send the appeal letter along with the documentation to the designated department of the insurance company, ensuring it is within the timeframe specified in the denial notice.
5. Follow Up: After submission, follow up with the insurance company to confirm receipt and inquire about the timeline for review.
It is advisable to keep copies of all correspondence and documentation submitted during this process for personal records.
Strategies for Presenting a Strong Case During the Appeal Process
Presenting a compelling case during the appeal process can significantly enhance the chances of overturning a denial. Here are some strategies to consider:
– Be Detailed and Specific: Clearly Artikel why the denial was incorrect, addressing each concern raised in the denial letter with factual evidence.
– Provide Additional Information: If circumstances have changed since the original application, provide updated information that could positively influence the underwriting decision.
– Consult Professionals: Seeking guidance from insurance agents or legal advisors can help in crafting a more persuasive appeal.
– Maintain Professionalism: Keep all communications polite and professional, as this promotes a constructive dialogue with the insurance company.
– Highlight Positive Aspects: If applicable, emphasize healthy lifestyle choices or stable medical conditions that reflect positively on the applicant’s overall risk profile.
Utilizing these strategies can significantly improve the likelihood of a successful appeal, making it essential for applicants to approach the process thoughtfully and thoroughly.
Epilogue
In summary, grasping Life Insurance Underwriting Requirements not only demystifies the insurance process but also empowers applicants to make informed decisions. With a better understanding of what insurers are looking for, individuals can approach their applications with greater assurance, ultimately leading to better coverage options and peace of mind.
Common Queries
What is the purpose of life insurance underwriting?
The purpose of life insurance underwriting is to assess the risk of insuring an applicant and determine appropriate premiums based on that risk.
Can I get life insurance with a pre-existing condition?
Yes, you can obtain life insurance with a pre-existing condition, although it may affect your premiums and coverage options.
How long does the underwriting process take?
The underwriting process can take anywhere from a few days to several weeks, depending on the complexity of the case and whether additional information is needed.
Do all life insurance policies require a medical exam?
No, not all policies require a medical exam; many insurers offer no-exam options for applicants who meet certain criteria.
What factors can disqualify me from getting coverage?
Factors that may disqualify you include severe health issues, high-risk occupations, or engaging in risky lifestyle choices.