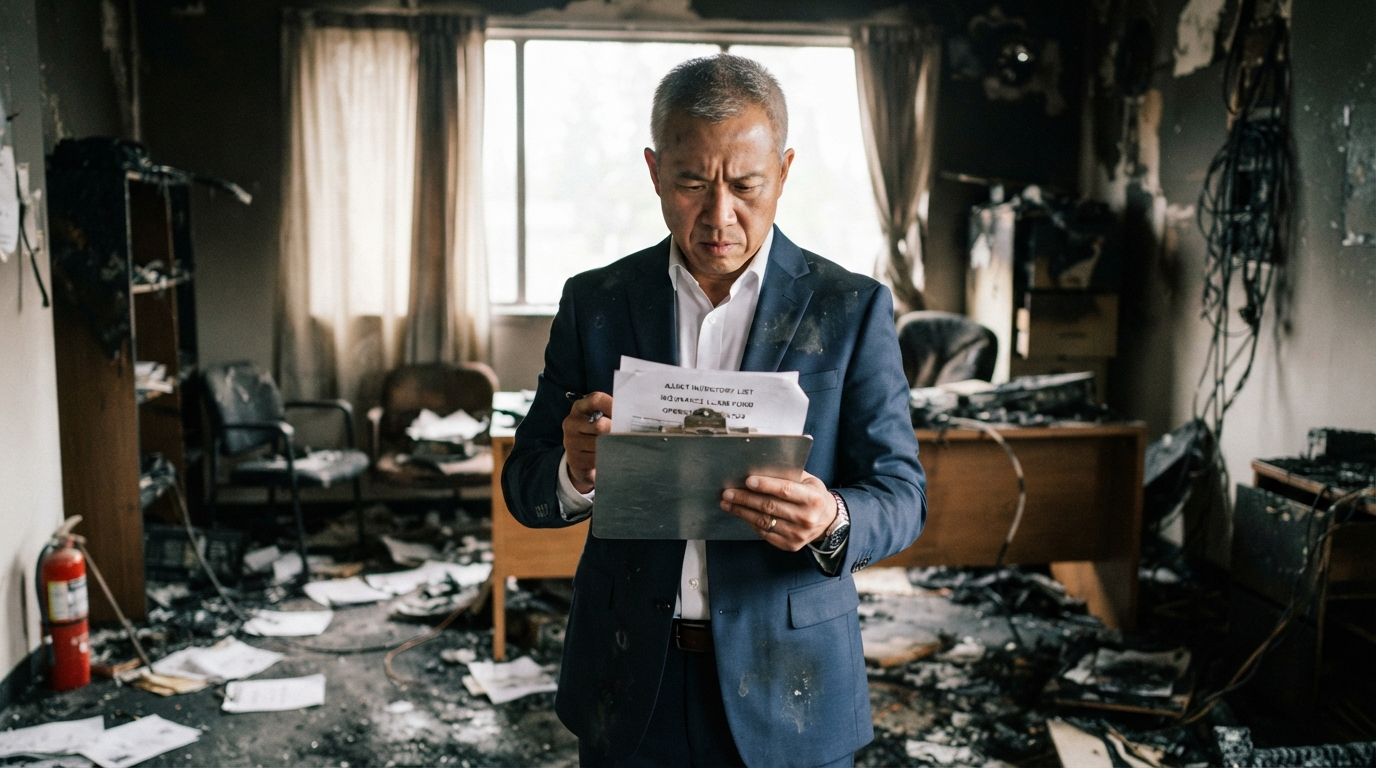
A fire, injury claim, or interrupted operation can threaten more than the asset directly damaged. Insurance Loss Exposure Analysis helps us assess how a US business could face financial harm. We can review the assets and operations at stake, then weigh protections that fit the organization’s needs.
A single loss may affect one building, while a wider disruption can affect income across several locations. Individuals face similar choices when a home, work, or health event strains their finances. A clear assessment helps us see where a loss could cause trouble before we make decisions about protection.
We can use a structured review to identify possible harm and estimate its scale. It also helps us compare insurance with other controls without treating either as a complete answer. The most useful analysis ends with clear priorities, named owners, and a date to review them.
Key Takeaways
- Separate the possible size of a loss from its likelihood.
- Review buildings, equipment, people, income, and operations.
- Use current records to support a sound assessment.
- Consider controls and insurance when choosing protections.
- Assign each action an owner and a review date.
What Does Insurance Loss Exposure Analysis Measure?
A warehouse has a potential fire loss before we know whether a fire will occur. An assessment describes that potential harm and its possible financial scale, while risk means the chance that harm will happen.
The National Association of Insurance Commissioners defines exposure as the possibility of loss. Pure risk has two possible outcomes: loss or no loss. Speculative risk has three: loss, gain, or break-even.
Keep potential loss and likelihood as separate entries in the assessment. A rare event can still carry a serious financial impact.
Insurance generally addresses pure risk, such as fire damage or an injury claim. These events may cause loss, but they do not offer a matching chance of financial gain. The terms of a policy still decide which events and costs qualify.
Speculative risk includes choices made to seek a gain, such as investing in a new venture. The venture could lose money, earn a profit, or break even. That range of outcomes usually places it outside standard insurance.
In practice, we can record a possible loss separately from our estimate of its chance. This keeps the description of an event distinct from the likelihood that it will occur. It also makes the review clearer when one event could threaten several assets or income streams.
Which Four Loss Exposures Should We Map?
A company can face a property loss and a liability claim from the same incident, but they affect different financial interests. Mapping four broad types helps us see which interests may be harmed.
Property, liability, personnel, and net income loss exposures cover the main business interests at stake. They give us a practical way to map types loss without treating every cost as the same kind of exposure.
Property and liability exposures
Property exposure includes real property, such as land and buildings, and personal property, such as equipment, tools, and inventory. A fire that damages a company’s equipment is a direct property loss. Theft or water damage can also harm insured property.
Liability exposure arises when a business may owe money for harm to someone else. A customer who slips on a wet floor may file a claim for an injury. The cost may include legal defense and a settlement or judgment, depending on the facts and coverage.
| Exposure type | What is at stake | Illustrative loss |
|---|---|---|
| Property | Buildings and business property | Fire damages equipment |
| Liability | Claims for harm to others | Customer injury claim |
| Personnel | Employee skills and capacity | Key employee becomes disabled |
| Net income | Revenue and operating costs | Revenue lost during closure |
Personnel and net income exposures
Personnel exposure includes loss tied to employee injury, disability, death, or departure. A key employee’s disability may disrupt work even when the building and equipment remain intact. The resulting costs can include hiring or training a replacement.
Net income exposure includes reduced revenue or increased expenses after a disruption. Business interruption is an indirect net income exposure, not physical damage itself. A closed site may lose revenue while the business still pays some operating costs.
One event may affect more than one row in the table. A fire could damage equipment, lead to a customer claim, and close a worksite. Map indirect costs and lost income alongside direct damage, because a damaged facility can create losses beyond its repair bill.
How Do We Measure Frequency and Severity?
A rare loss can still deserve attention when its potential cost is large. We estimate frequency as how often claims occur and severity as the average cost per claim.
Frequency multiplied by severity gives a pure loss cost before added loads. An insurance loss exposure analysis formula can also estimate one event’s cost, its annual rate, and the resulting annualized loss expectancy.
Estimate how often losses may occur
Claim frequency counts claims per exposure unit. For example, 0.13 claims per 100 house-years means the measure is tied to 100 homes observed for one year. A rate describes a group, not a promise about any one home.
Estimate the cost of a loss
Claim severity is the average loss per claim. Single loss expectancy estimates the cost of one event: asset value multiplied by the share damaged. The estimate changes when either the asset value or the assumed damage share changes.
Combine frequency and severity
Annual rate of occurrence estimates how often an event may happen in a year. Annualized loss expectancy equals single loss expectancy multiplied by that annual rate. These are planning estimates, not exact forecasts of next year’s claims.
| Measure | What it captures | Calculation or expression |
|---|---|---|
| Frequency | Claims per exposure unit | Claims divided by exposure units |
| Severity | Average loss per claim | Total loss divided by claims |
| Single loss expectancy | Estimated cost of one event | Asset value × share damaged |
| Annual rate of occurrence | Expected event rate each year | Estimated events per year |
| Annualized loss expectancy | Estimated annual loss | Single loss expectancy × annual rate |
In 2024, non-catastrophe homeowners fire claims had an average severity of $173,111 per claim. Their frequency was 0.13 claims per 100 house-years in that year. Read together, the figures show why a low rate and a high average cost need separate attention.
Frequency and severity support planning, but neither predicts the next year’s exact result. A handful of large claims can shift an average, while changing conditions can shift the rate. Record the assumptions behind each estimate so we can update the calculation when exposure conditions change.
What Information Makes an Exposure Assessment Useful?
Start with records that describe what the organization owns, does, and earns today. An exposure basis is the unit an insurer uses to measure the amount of risk being insured, such as payroll or building value.
The right exposure basis depends on the coverage and the operation it measures. Payroll, receipts, sales, square footage, and man-hours are common examples. A sound measure should reflect the exposure, be easy for an insurer to determine, and be hard for the insured to manipulate.
For example, payroll may fit a coverage tied to employee work, while square footage may help describe a building exposure. Revenue or sales can help describe business activity. A measure that does not match the operation can give insurers a distorted view.
We can gather records in five practical groups:
- Current asset and building values.
- Payroll and employee information.
- Revenue and sales records.
- Locations, processes, and key suppliers.
- Claims, safety, and incident records.
Property details can include construction, location, use, replacement value, claims history, and safeguards such as alarms or sprinklers. These details help explain how a building is used and what might affect its losses.
Outdated payroll, revenue, or property values can distort the picture insurers use to evaluate coverage. A staffing change, new production process, or added location may also make an old record less useful. Compare the records with current operations before using them to support a coverage or risk decision.
Our assessment methods should fit the decision and the quality of the records. A property risk assessment approach can help frame how building details and safeguards affect an insurer’s review. Compare the records with current operations before using them to support a coverage or risk decision.
How Do Catastrophe Models Estimate Property Loss?
A catastrophe model estimates loss by matching plausible events to the locations and properties that could be affected. Its four modules turn event details and property information into financial estimates.
Model results depend on exposure detail and event assumptions. A model can estimate damage from a plausible event even when that event has not happened in the historical record.
The four modules in a catastrophe model
The event module creates stochastic scenarios, or modeled events, with a strength, location, and probability of occurrence. It gives the model a set of possible events to test against the exposure.
The hazard module assesses physical danger across the geography at risk. The vulnerability module estimates how much structures and insured property may be damaged by that hazard. Different buildings can respond differently to the same event.
The financial module turns estimated physical damage into monetary loss. It also determines who is responsible for paying under the financial terms represented in the model. These four roles work together, but each answers a different question.
AAL and PML answer different questions
Average annual loss (AAL) is the long-term average annual catastrophe loss for an exposure. It supports comparisons of expected losses across a portfolio over time.
Probable maximum loss (PML) is potential catastrophe loss over a selected return period, such as 250 or 500 years. It describes a possible loss level tied to a return period, rather than an annual average.
What portfolio outputs can reveal
Geographic outputs can show which locations drive a portfolio’s property loss estimates. A group of buildings in one hazard area may contribute more to modeled losses than scattered sites. That pattern can help decision-makers see where values are concentrated.
Models can also estimate damage from a plausible event that has no historical match. This does not make the estimate a forecast of a specific event. The result depends on the modeled event, property details, and assumptions about damage and policy terms.
Even detailed outputs can shift when property values, locations, or event assumptions change. Review both the modeled loss measure and the assumptions behind it before using an estimate to make a capital or coverage decision.
A fuller review of catastrophe risk assessment can help us understand how hazard, building, and policy details shape an estimate.
How Do Insurers Use Exposure and Claims Data to Price Coverage?
Two employers in the same industry can face different premiums when their exposure details or claims histories differ. Exposure rating estimates expected loss from exposure and class information; experience rating adjusts a premium using an employer’s past payroll and losses.
The main difference is the data and comparison baseline, not which method is always better. Each approach can help price coverage, but each relies on different information.
Exposure rating vs. experience rating
| Comparison | Exposure rating | Experience rating |
|---|---|---|
| Data used | Exposure and class details | Employer payroll and loss records |
| Comparison baseline | Expected losses for the exposure | Similar employers’ experience |
| Typical purpose | Estimate expected loss | Adjust premium for past losses |
| Key limitation | Depends on exposure details | Depends on credible claim history |
Exposure rating uses information about the insured operation and its class to estimate expected loss. Experience rating compares an employer’s record with similar employers. Neither approach removes the need for accurate classification and exposure information.
For more on the factors that shape a quote, see commercial insurance premium methods. Business type, location, employee duties, payroll, revenue, and claim history can affect pricing.
How workers compensation experience rating works
In 2025, workers compensation experience rating compared an employer’s record with employers in the same classification. The calculation used payroll and loss records to set a modification that could raise, lower, or leave premium unchanged.
The latest available three years of employer data are usually compared with similarly grouped employers. Frequency receives greater weight than severity because an individual accident’s cost is less predictable than whether an accident occurs.
The plan divides each historical claim at a primary/excess split point. Primary losses fall below that point and receive greater weight; excess losses fall above it. A state accident limitation caps the amount from one claim that can affect the modification.
For example, when the state per-claim accident limit is $200,000, a $500,000 individual loss is capped at $200,000 for experience-rating purposes. The state per-claim accident limit is one part of the calculation, while the plan’s split point affects how each claim is divided.
Check the applicable state plan and classification rules before using an experience modification to forecast a premium.
Which Risk Treatment Fits Each Exposure?
A business can reduce a fire exposure with prevention, transfer part of the financial impact through insurance, or combine both approaches. The right risk treatment reflects the chance of loss and the harm it could cause.
Four common choices are avoidance, loss reduction, retention, and transfer. Insurance is one way to transfer financial impact, but controls and retained funds can also play a role.
Avoid the activity or reduce the chance of loss
Avoidance means stopping an activity that creates an exposure. A business might remove a hazardous process if the work is not needed. Loss reduction keeps the activity but lowers the chance or likely size of loss, such as adding fire alarms or safer work steps.
Retain manageable losses or transfer them
Retention means paying some losses with the organization’s own funds. It can suit smaller costs that the business can absorb. Transfer shifts part of the financial impact to another party, often through property, liability, or business interruption coverage.
Policy wording controls what insurance covers. Some property policies use an 80% replacement-cost coinsurance threshold, but the policy terms determine whether and how that provision applies. The threshold is not universal.
Match the response to severity and frequency
A frequent, manageable loss may call for stronger routine controls and a budget for retained costs. A rare event with severe consequences may call for insurance and added safeguards. A business interruption policy may address covered income loss and specified extra expenses, subject to its terms.
- Avoidance: stop a hazardous activity that the business can do without.
- Loss reduction: add safety controls where the work must continue.
- Retention: budget for small losses the business can afford.
- Transfer: buy coverage for losses that could strain the business.
Deductibles and retained losses should fit available cash and the business’s ability to recover after a claim. A higher deductible can lower the premium but leaves more of a covered loss with the business. Confirm limits, deductibles, exclusions, and any coinsurance clause against the exposure the organization intends to protect.
How Can We Monitor Claims and Accumulated Exposure?
One regional event can generate related claims across multiple properties or lines of coverage. This creates accumulation risk, the potential loss exposure when one event spreads across multiple lines of business.
Monitoring claims and geographic concentrations helps us see where one event could affect several parts of a portfolio. An insurer can track claim patterns alongside the locations and coverage tied to each risk.
Global insured natural-catastrophe losses totaled $137 billion in 2024. A large event can affect several locations, policies, or lines at once, even when each policy covers a separate interest.
Catastrophe models can help insurers price policies, set reserves, and assess reinsurance needs. Reinsurance can reduce an insurer’s net loss after covered losses meet the relevant contract terms. It does not remove the underlying exposure or guarantee recovery.
Monitoring can flag clusters of insured property in one region and repeated claims tied to a location or operation. An insurer may also compare modeled events with its coverage mix to see where one loss could affect several lines.
Our business review should track new sites, changing operations, and claim patterns. Revisit concentration points after acquisitions, new locations, or changes to the organization’s insurance program.
What Does an Exposure Analysis Look Like in Practice?
Imagine a small hotel that knows its staff safety procedures but has not reviewed how a building closure could affect income. An insurance loss exposure analysis example can show how the owner turns records into practical decisions.
The owner can move through four stages, from gathering facts to checking whether actions work. The review includes fire, guest injury, staff injury, and business interruption concerns.
First, the owner inventories the hotel’s locations and operations, then reviews property, payroll, revenue, safety, and claims records. The owner considers how each event could affect people, property, and income, then ranks the potential impacts.
A useful assessment gives every agreed action an owner and a review date. Without those two details, important work can remain unfinished.
The owner assigns each action to a person responsible for carrying it out. The team then schedules a follow-up to check whether the actions changed the hotel’s exposure or response.
The four stages are:
- Collect information about property, people, and operations.
- Analyze and prioritize the exposures.
- Implement the agreed recommendations.
- Monitor results and schedule a follow-up.
At the follow-up, the hotel can compare completed actions with its original priorities. New operations or updated records may change what deserves attention. Give each agreed action an owner and a review date so the assessment leads to follow-through.
Conclusion
Better protection starts with a clear picture of what could cause financial harm and how the organization would respond. Current information helps us set priorities that fit the business rather than rely on old assumptions.
Exposure analysis works best as a repeatable decision process. Controls can lower the chance or impact of harm, while insurance can help address covered costs. Neither replaces a clear view of changing operations.
Schedule a review of the organization’s current asset, payroll, operations, and coverage records with the people responsible for those areas. Set a date for the review and identify who will bring each record.