A missed supplier delivery, workplace injury, cyber incident, or severe storm can disrupt a business even when its owners are making careful decisions. U.S. business owners face uncertainty across daily operations, staff, property, finances, and information. A repeatable plan helps us spot exposures before they grow into costly losses. The risk owner is the person accountable for coordinating action on a specific identified risk. We can use that role to keep decisions from stalling between teams. Insurance can help pay for certain losses, but it cannot prevent an injury, restore trust, or keep every operation running. Prevention and planning still matter. This guide offers a practical way for organizations to connect day-to-day safeguards with financial protection. A useful risk plan connects prevention, response, and financial protection to the exposures that matter most to the company.
Key Takeaways
- Identify exposures across the business, not within one team alone.
- Choose a response that fits each risk’s likely impact.
- Name a risk owner and set a deadline for action.
- Use insurance to address financial losses, not as a substitute for prevention.
- Review plans when the business, its systems, or its location changes.
What Risks Should a Business Identify First?
A business can start its risk inventory by sorting possible losses into four broad categories. This simple first step helps us look beyond the problems one team sees each day. Include risks that could affect money, legal duties, or future plans, as well as daily operations.
Operational risk can come from failures in processes, people, systems, or outside events. A software outage that stops orders is one example. Financial risk includes credit pressure and cash-flow problems, such as customers paying late while payroll comes due.
Legal and compliance risk involves breaking laws, rules, or contracts. A privacy violation or missed workplace rule can bring fines or legal claims. Strategic risk can follow a new-market decision or reliance on one supplier for a key part.
- Operational: A payment system fails during a busy sales period.
- Financial: Late customer payments leave too little cash for bills.
- Legal and compliance: Staff mishandle private customer data.
- Strategic: One supplier provides nearly all critical materials.
Invite people from different teams to name risks together, since one department may miss an exposure another team handles every day.
Cross-functional discussions bring together staff who see different parts of the same process. A finance lead may notice unpaid invoices, while operations sees the supplier delays behind them. That shared view gives organizations a fuller risk management picture.
Write each risk in plain terms, then note where it could disrupt the business. Record near misses as well as actual losses, since either can reveal a weak process.
How Do Insurance Risk Mitigation Strategies Fit Into a Risk Plan?
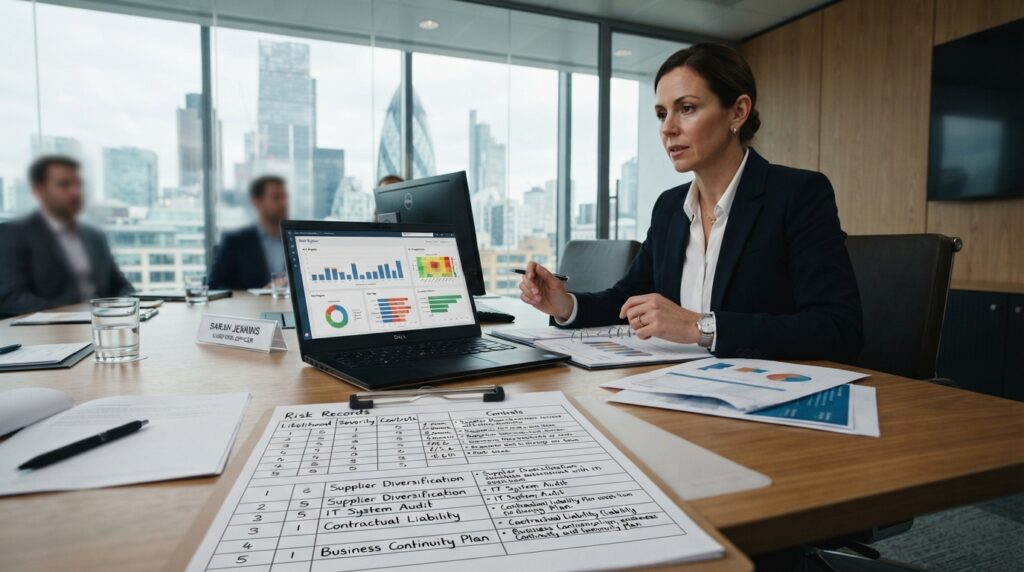
A small payment-processing error may call for a different response from a fire that could close a facility. We choose among four common responses by weighing the likelihood and severity of each risk. Insurance can transfer some financial consequences, but not the underlying risk.
We can use a risk assessment method to compare a risk’s likelihood and impact against clear criteria. Examples of Insurance Risk Mitigation Strategies range from changing a process to ending an activity. The best insurance risk mitigation strategies depend on the exposure, the cost of action, and the loss we can bear.
Which Risk Mitigation Response Fits the Exposure?
These four risk mitigation strategies are common choices, not a universal list of every technique. Some frameworks describe sharing, buffering, testing, or digital tools as added techniques. A few also count sharing as a separate response.
| Response | What it does | When it fits | Example |
|---|---|---|---|
| Avoidance | Ends the activity creating the risk | Exposure is unacceptable | Leave a market with unsafe conditions |
| Reduction | Lowers likelihood or severity | Controls can limit exposure | Add a review step to catch payment errors |
| Transfer | Shifts some financial cost | Another party can take agreed costs | Buy insurance or add contract terms |
| Acceptance | Keeps the risk with the business | Potential loss is low and manageable | Retain the cost of minor supply delays |
Insurance does not transfer every cost. A business may still pay deductibles, and exclusions can leave some losses uncovered. Contract terms may shift costs, but they do not remove the event itself.
How Do We Put Risk Responses Into Practice?
Score likelihood and severity on a simple scale, such as low, medium, or high. For risks with useful cost estimates, expected monetary value equals probability multiplied by monetary loss. A 10% chance of a $20,000 loss has an expected monetary value of $2,000.
A risk owner should work in the area affected and have authority to act. Record the chosen control, its owner, deadline, needed resources, and measure of success. The IMD risk management overview also describes identifying, assessing, treating, and monitoring risks.
Preventive controls stop problems before they happen; detective controls find them. Corrective controls fix problems, directive controls set expected behavior, and compensating controls provide another safeguard when a preferred control is not possible.
These are control types, not five more risk responses. Risk mitigation examples include adding an approval step, ending an unsafe service, insuring a costly loss, or accepting a small deductible. Some people search for five risk mitigation strategies, but the framework must be named before adding a fifth choice. Assign each high-priority action an owner, a deadline, and a measure that shows whether the exposure is falling.
Which Controls Lower Workplace and Disaster Losses?
If a machine guard can remove an exposure, that is generally a stronger control than relying only on a warning sign or protective equipment. The OSHA hierarchy ranks workplace hazard controls from most to least effective. Choose controls that prevent exposure at its source whenever practical.
Elimination removes the hazard, while substitution replaces it with a safer option. Engineering controls isolate workers from danger. Administrative controls change work rules or schedules, and personal protective equipment, or PPE, protects the worker directly.
How Does the Hierarchy of Controls Apply at Work?
Workers should help evaluate whether a control is feasible, effective, and lasting. Their hands-on knowledge can show where a machine jams or a work step creates strain. Use interim controls while the team develops longer-term measures.
Review hazard-control plans at least once a year and when workplace conditions, processes, or equipment change. A new machine can alter how staff move through a work area, even when the room stays the same.
How Can a Business Prepare Its Facility and Critical Operations?
Follow applicable fire rules and building codes when choosing and maintaining a site. Consider local hazards before signing a lease or buying property. Critical equipment may need an uninterruptible power supply, or UPS, or a standby generator.
- Fire protection: Check alarms, sprinklers, exits, and inspection records.
- Site hazards: Review flood, storm, and earthquake exposure before choosing a location.
- Backup power: Confirm UPS units or generators support critical equipment.
- Recovery procedures: Keep written steps for restoring key operations.
NFIP flood coverage may be available for a facility in a flood zone. Earthquake, terrorism, and pollution coverage may require separate policies or endorsements. These choices can affect compliance, property protection, and the systems needed to keep work moving.
Review controls after a process or equipment change instead of waiting for the next annual review.
How Can Insurance Transfer Financial Risk Without Leaving Coverage Gaps?
Insurance conditions are not moving in one direction: property pricing eased in early 2026 while several liability lines continued to rise. We can use policies to finance covered losses, but coverage terms matter as much as the premium. Match each policy’s trigger, limits, exclusions, and deductible to the loss it should address.
Commercial property premiums fell by an average of 5.5% in the first quarter of 2026. Yet catastrophe-exposed accounts in Florida, California, and Gulf Coast markets still faced firm pricing, despite improved terms and lower deductibles than a year earlier.
What Is Changing Across Commercial Insurance Lines?
Average premiums across commercial property and casualty accounts fell 1.2% in the first quarter of 2026, with nine lines posting decreases. Commercial auto, umbrella, and general liability continued to rise.
Policy limits and deductibles can affect premium costs, so compare quotes with matching terms. Commercial auto premiums rose 5.8%, marking the 59th consecutive quarter of increases. General liability rose 2.6%, while umbrella premiums rose 4.8%.
Most first-layer umbrella towers were capped at $5 million to $10 million in early 2026. Carriers willing to provide $25 million or more in one layer had become scarce. Global reinsurance capital exceeded $700 billion entering 2026, a record high.
What Do Small-Business Policies Cost?
Insureon customer medians below reflect policies bought by 100,000 customers, not market-wide quotes. Cyber insurance had a median monthly cost of $129, and commercial umbrella coverage had a median of $86.
| Policy type | Insureon customer median monthly cost |
|---|---|
| General liability | $45 |
| Business owner’s policy | $83 |
| Professional liability | $88 |
| Workers’ compensation | $54 |
| Commercial property | $108 |
For general liability, a $1 million per-occurrence limit and $2 million aggregate limit averages $45 monthly. Limits of $2 million per occurrence and $4 million aggregate average $46 monthly. The average deductible selected by Insureon customers is $500.
Most states require workers’ compensation for businesses with employees, but rules vary by state. Business interruption insurance is optional and may come in a commercial multi-peril policy. It usually requires direct physical property loss from a covered peril to trigger coverage.
Some policies may add contingent coverage for supplier failure or an extra-expense endorsement. Read the wording closely, since a supplier delay alone may not meet the policy’s trigger. Check the policy’s trigger, exclusions, limits, and deductible against the loss the business is trying to finance.
How Can Businesses Reduce Cyber and Health-Plan Exposure?
A documented control can make a cyber insurance application easier to answer and expose a security gap before an incident. We can track proof of safeguards in the same place as our risk management records. Applications commonly ask about security steps, backups, staff training, and vendor risk.
Keep records for multi-factor authentication (MFA) on email, remote access, and administrator accounts. Document endpoint protection on every device, plus tested offline or immutable backups. An immutable backup cannot be changed or deleted for a set period.
Which Cyber Controls Help With Insurance Applications?
Maintain an incident response plan, staff training records, and a list of key vendors. Classify data by sensitivity so staff know which information needs tighter controls. These steps answer common application questions and clarify who handles each task.
U.S. direct written cyber premiums fell 7.11% to $9.14 billion in 2024, while policies in force stayed near 4.37 million. The U.S. cyber insurance loss ratio was 47% in 2024, the third profitable year in a row for carriers.
In 2025, initial ransomware demands rose 47% to more than $1 million. Still, 86% of affected Coalition policyholders refused to pay. Those market figures do not predict an individual company’s risk or premium.
Business risk management calls for regular review as threats and operations change. A written cyber plan should name who can isolate a device, contact vendors, and report an incident.
How Can Employers Manage Health-Plan Risk?
Fully insured employers pay a set premium, and the insurer pays covered claims. Self-funded employers pay claims directly, so costs can change with employee health needs. Stop-loss insurance can cap a self-funded employer’s exposure at a set dollar amount.
Employers expect total health benefit costs per employee to rise 6.5% on average in 2026. Without cost-reduction steps, employers estimated costs could rise by 15% or more. Pharmacy spending made up 24% to 30% of employer healthcare costs in early 2026.
Specialty medications made up fewer than 5% of prescriptions but were projected to account for more than 60% of pharmacy spending in 2026. High-cost claims rose 61% over four years, and nearly 90% of self-funded employers experienced catastrophic expenses.
About 67% of U.S. employers that offer health insurance are self-funded; 33% are fully insured. Employers can review plan design, pharmacy exposure, and stop-loss terms to manage health insurance risk. ACA Marketplace risk adjustment shifts funds among Marketplace plans with different member risk levels. It does not cap claims for an employer’s self-funded plan.
A completed checklist cannot show whether people can restore data or carry out their roles under pressure.
Test backup restores and incident-response roles in practice, rather than relying on a completed checklist alone.
Conclusion
A workable risk plan is one the people responsible for the business can act on and update. We get better results when each action has a clear owner and fits the company’s real operations. Prevention and financial protection work best when they support each other.
Set a short meeting with the people responsible for operations, finance, safety, and technology. Choose one priority exposure, then record its owner, action, and review date. Keep the decision brief enough for the team to use during busy workdays.
Put the first review date on the calendar before the meeting ends.