A client dispute over advice, a missed deadline, or an unfinished project can create legal costs even for a small firm. Professional liability insurance can help address claims tied to paid services, including work by a one-person business. The best fit depends on your services, budget, and coverage needs.
We’ll compare insurance providers, explain what this coverage can do, and point out policy terms to check. Client contracts may also shape your choice, especially when they set coverage limits or require proof of insurance. The right policy should match the work you do and the contracts you sign.
Key Takeaways
- Match coverage to the services your business provides.
- Compare policy terms, limits, and deductibles, not just premiums.
- Check whether a client contract or license requires coverage.
- Understand when a claims-made policy can cover past work.
- Confirm that the insurer writes policies in your state.
- Keep claims-made coverage continuous when changing insurers.
Best Professional Liability Insurance for Small Businesses
The Hartford is a practical first look for owners who want to consider professional liability and a BOP together. For online purchase, ERGO NEXT, formerly NEXT Insurance, offers a direct route. The best professional liability insurance for small businesses in the USA depends on the work, state, and policy terms.
Start with the provider that fits how you want to buy and what your business does. The table gives five options, while Philadelphia Insurance Companies and CM&F Group add two more names to a shortlist. A high rating speaks to an insurer’s financial strength, not whether one policy suits your work.
Choose a provider for its fit with your work and buying needs, then compare the policy itself.
| Insurer | AM Best rating | Stated coverage footprint | Practical fit |
|---|---|---|---|
| The Hartford | A+ | Nationwide except Alaska and Hawaii | Consider professional liability with a BOP |
| ERGO NEXT | Not listed here | Not listed here | Online quotes and purchase |
| Hiscox | A (Excellent) | Nationwide except Alaska | International work; U.S. or Canadian claims |
| Travelers | A++ | Nationwide | Agent support for quotes and purchase |
| Chubb | A++ | Nationwide | Online access below $2 million in revenue |
Chubb applicants with more than $2 million in revenue need agent help. Travelers also requires an agent for quotes and purchases. The Hartford offers professional liability with a BOP, though some customers may need a phone call to finish buying.
Hiscox may cover work performed worldwide when claims are filed in the United States or Canada. Prior-acts coverage may be available if another insurer covered the business when the incident happened. For financial strength, AM Best rates The Hartford A+, Hiscox A (Excellent), and Chubb and Travelers A++.
AM Best describes its Financial Strength Ratings guide as an opinion of an insurer’s ability to meet ongoing obligations. The scale runs from Superior, A++ or A+, to Poor, D. The rating does not assess a particular policy or guarantee future credit quality.
ERGO NEXT coverage starts at $19 per month for some low-risk businesses. Industry, business size, location, limits, deductible, experience, and claims history affect the price. The Hartford is unavailable in Alaska and Hawaii; Hiscox is unavailable in Alaska. Philadelphia Insurance Companies is unavailable in Louisiana, while CM&F Group offers coverage nationwide.
A search for The Hartford professional liability insurance may lead owners to its bundled BOP option, but some purchases need a call. These companies are case-specific options, not one universal winner. Confirm that the insurer writes coverage in your state before comparing quotes.
What Does Professional Liability Insurance Cover?
A client who says a missed deadline caused a financial loss may bring a claim even if the professional believes the work was reasonable. Professional liability can help cover legal defense costs and covered losses, subject to policy terms. Alleged mistakes may lead to a claim even when a business believes it did nothing wrong.
Defense costs and covered damages remain subject to policy limits and exclusions. A consultant may face a claim after a flawed plan leads a client to lose money. An IT firm may face one after a data migration damages a client’s records.
Mistakes, missed deadlines, and omissions
An accountant’s calculation error could prompt a client to allege financial harm. Other claims may involve inaccurate advice or a service that the client says was incomplete. The allegation, not proof of a mistake, can start a dispute.
Common claim situations include:
- Inaccurate advice that leads to a financial loss
- A missed deadline that affects a client’s plans
- Failure to deliver a service promised in an agreement
- Alleged negligence in professional work
Legal defense and covered client losses
A policy may help pay for legal defense when a client alleges negligence, an error, or an omission. Coverage depends on the policy wording, limits, and exclusions. The insurer may still respond to an allegation when the business disputes the client’s account.
Defense expenses can affect how much remains to pay a covered loss. Review whether defense expenses reduce the policy limit or are paid outside it.
What Does Professional Liability Insurance Not Cover?
A client’s financial loss from bad advice is a different exposure from a visitor’s injury at your office. Professional liability usually addresses service errors that cause financial harm, while general liability insurance can address third-party bodily injury and property damage. Separate risks may call for separate policies.
Professional liability typically does not cover bodily injury. A visitor who slips in an office may have a general liability claim. Damage to someone else’s property may also fall under general liability, depending on the facts and policy.
Patient injury claims tied to professional care may call for medical malpractice insurance. That coverage can address claims that professional work worsened a patient’s condition or caused an injury. Exact protection depends on policy wording.
A technology service failure and a cyber incident are not the same risk. Tech E&O can cover technology errors or service failures that cause a client financial loss. A data breach or malicious software attack may require cyber liability coverage.
Some insurers bundle Tech E&O with cyber liability, but the terms still matter. A single event can involve a service failure and a data breach, so more than one policy may come into play. Read the exclusions and definitions together, since a claim can involve more than one type of loss.
Which Businesses Need Professional Liability Insurance?
A business should consider this coverage when a client could claim that its advice or service caused a financial loss. Consultants, accountants, financial advisors, and many other service providers may face that kind of allegation. Even solo owners can face claims like those against larger firms.
Paid advice or client work can create professional-error exposure. A one-person business may sign the same type of contract or make the same kind of recommendation as a larger company. The number of employees does not remove the risk.
Advice, consulting, and financial services
Consultants may guide a client’s business plans, while accountants and financial advisors handle choices with financial effects. Healthcare workers also provide professional services that can lead to claims. Each business should consider what a client could lose if advice or work falls short.
Technology, design, and other client services
IT professionals, engineers, architects, and real estate professionals may need coverage for claims tied to services. A software project, building plan, or property inspection can affect a client’s money or business plans. Licensing rules and client contracts may require professional liability insurance.
Use these four checks to judge whether the exposure applies:
- Do clients rely on the business’s advice?
- Could a service error cause a client financial loss?
- Do client contracts require professional liability coverage?
- Do licensing rules apply to the business’s work?
A client may allege harm even if the business believes it met the agreement. That makes the scope of the service and the client’s reliance worth reviewing. Check both licensing rules and client contracts, since either can set a coverage requirement.
How Much Does Professional Liability Insurance Cost?
A 1-to-4-person business with a $1 million per-claim and $2 million aggregate policy has a 2026 benchmark of $56 per month, or $675 per year. That figure applies to a defined business size and policy structure. Broader estimates describe different groups and should not be treated as the same price.
The $56 monthly benchmark is not a quote for every small business. Profession, location, business size, experience, limits, deductible, exclusions, coverage options, and claims history can shift a premium. Employee count and years in business also affect pricing.
Published premium benchmarks
One 2026 analysis puts the national average at $56 per month, or $675 per year, for a 1-to-4-person business with the stated limits. A broader 2026 estimate gives an average of $88 per month, with annual premiums ranging from $380 to $7,400.
A separate small-business estimate places professional liability at $45-$76 per month, or $540-$912 per year. The median premium for small-business professional liability or E&O customers is also $88 per month. An average and a median describe different measures, and neither guarantees an individual price.
The $56 figure is tied to a specific policy limit and business size, while the $88 average and median cover broader customer groups. The separate $45-$76 range is another estimate, not a direct comparison with those figures. A 2026 cost analysis gives the $56 benchmark and its policy conditions.
What changes the premium
A business with a higher-risk service, more employees, or a history of claims may receive a higher quote. Larger limits and broader coverage options can also raise the price. A higher deductible may lower the premium but leaves the business paying more toward a covered loss.
Location, years of experience, and the policy’s exclusions can also affect cost. Compare quotes only when they use the same limits, deductible, and coverage terms. Compare quotes using the same limits, deductible, and coverage terms before judging which premium is lower.
How Much Professional Liability Coverage Do You Need?
A $1 million per-occurrence and $1 million aggregate limit is a common professional liability starting point for a small business. That structure sets one cap for a claim and another cap for all covered claims during the policy term. Some businesses may need a higher limit.
Match limits to contract terms, likely claim size, and the losses your business could absorb. Professional liability limits can range from $250,000 to $2 million, and higher limits generally increase the premium. A common starting point is a benchmark, not a required choice.
The per-claim limit sets the most the policy pays for one covered claim. The aggregate limit sets the most it pays for all covered claims during the policy term. Two claims can use up the aggregate even when neither reaches the per-claim cap.
A common small-business limit is $1 million per occurrence and $1 million aggregate. A 2026 cost benchmark for a 1-to-4-person business uses $1 million per claim and $2 million aggregate. Those structures differ because the second allows a higher total payout across multiple claims.
Review client contracts for stated limits, then consider how much one serious claim could cost. Think about whether the business could pay losses above the policy limit without putting operations at risk. Match the aggregate limit to the number and potential size of claims the business could face during a policy term.
Claims-Made vs. Occurrence Coverage
Claims-made coverage generally requires both an eligible incident date and a claim filed while the policy is active. An occurrence-based policy generally responds when an incident happens during its policy period, even if the claim comes later. The timing trigger is the key difference.
A claims-made policy can cover an incident only when it falls on or after the retroactive date and the claim is filed during active coverage. The retroactive date is the earliest incident date the policy may cover. Reporting terms in the policy still apply.
| Policy trigger | Claims-made policy | Occurrence-based policy |
|---|---|---|
| Incident date | On or after the retroactive date | During the policy period |
| Claim-reporting timing | While the policy is active | May be filed later |
| Policy trigger event | Eligible incident and timely claim | Incident during the policy period |
| After policy period | Later claims need continued protection | Later claims may still be reported |
A retroactive date does not mean every earlier incident qualifies. The claim must still be filed while the claims-made policy is active, and the wording may set a reporting deadline. An occurrence-based policy instead looks to when the event happened.
Claims-made-and-reported policies may require the business to report a claim within a set time. IRMI explains how claims-made reporting rules can affect coverage when notice arrives late. The policy wording controls the deadline and other reporting steps.
The two triggers can lead to different results for the same late-reported dispute. Check the policy’s retroactive date before relying on coverage for earlier work.
What Are Tail Coverage and Prior Acts Coverage?
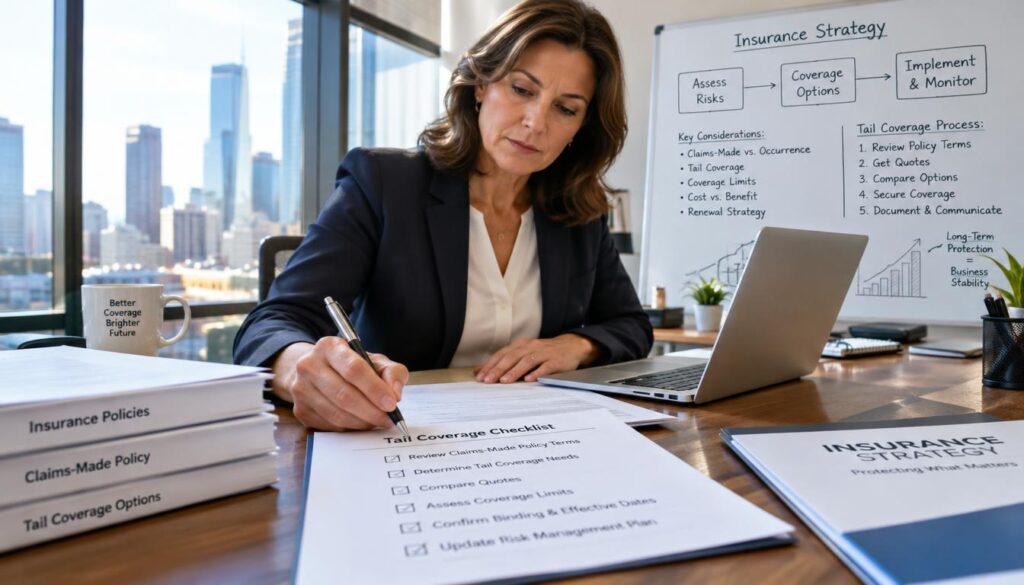
A claims-made policy ending does not automatically give the business extra time to report a later claim. Tail coverage can extend the reporting period for qualifying claims tied to incidents during the policy term. Continuity matters when a business ends or changes coverage.
Plan for reporting rights before a claims-made policy expires. Without tail coverage or suitable prior-acts coverage, a business may lose protection for earlier work. The right option depends on whether the current policy ends or a new insurer takes over.
Tail coverage after a claims-made policy ends
Tail coverage lets the business report qualifying claims after the policy ends. It does not make later work eligible; the incident must have happened while the original policy was active. The claim must also meet the policy’s terms.
Claims-made policies generally cost less at first than occurrence-based policies, but premiums can rise as the policy matures. Tail coverage can cost 1.5 to 3 times as much as an occurrence-based policy. That is a general cost warning, not a quote for a specific insurer.
Prior-acts coverage when changing insurers
Prior-acts coverage under a new policy may preserve protection for work done before that policy began. The new policy’s retroactive date affects which earlier incidents may qualify. The claim must still meet its reporting terms.
When switching insurers, a business may need prior-acts coverage from the new insurer or tail coverage from the old one. Either choice can help prevent a gap in protection for past work. Arrange the replacement policy’s retroactive date or tail coverage before the current policy expires.
What Should You Compare in a Professional Liability Policy?
Two policies with the same premium can leave a business with very different uncovered risks. Compare the wording, limits, reporting terms, and claims support before choosing. The price alone does not show how much risk stays with the business.
Use the same limits and deductible when comparing quotes. Otherwise, a lower premium may simply come with less coverage or more out-of-pocket cost. Contracts may also require specific limits or proof of insurance.
Check these five parts of each policy:
- Per-claim and aggregate limits
- Deductible and the business’s share of a covered loss
- Exclusions and coverage limitations
- Retroactive date and claim-reporting terms
- Claims handling and customer service
A higher deductible may reduce the premium, but the business must pay more before coverage responds. Exclusions can also remove protection for certain work or losses. Read the policy terms that define what counts as a claim and how the insurer handles notice.
Claims handling can affect how quickly the business gets help after a client complaint. Check whether the insurer sets deadlines for reporting claims or circumstances. Keep a copy of the policy and compare its terms against any contract requirements before binding coverage.
Which Providers Fit Your Profession or State?
The best starting list changes by profession: an IT firm’s options are not identical to an accountant’s. The names below are comparison starting points, not proof that a policy fits. Business insurance companies may offer different terms for the same type of work.
Match each insurer’s policy to the exact services and state involved. The table lists provider options by profession, while Texas and California usage data offer another way to build a shortlist. Popularity does not show how a policy handles a particular claim.
| Profession | Listed provider options | Practical comparison note |
|---|---|---|
| IT and technology | The Hartford, PHLY | Compare technology service wording |
| Consultants | Hiscox, PHLY, The Hartford | Check which consulting work is covered |
| Healthcare | Hiscox, CM&F Group | CM&F policies are written by The Medical Protective Company |
| Accountants | Hiscox, The Hartford, Berkley Management Protection | Compare accounting service definitions |
| Engineers | The Hartford, Hiscox, Beazley | Check coverage for the firm’s engineering work |
In 2026, The Hartford, Hiscox, and PHLY were Texas customers’ three most-used professional liability insurers. California customers most often used The Hartford, Hiscox, and CM&F. These trios answer common searches for the best professional liability insurance for small businesses in Texas and California, but usage is only a starting point.
Availability and wording may vary by state and service. A provider used by many businesses may still exclude work that matters to a particular firm. Check eligibility and policy language for the state where the business operates.
Ask each provider whether its policy matches the services and state in which the business operates.
When Is Professional Liability Insurance Required?
A professional liability policy is not required for every business, but a licensing rule or signed contract can make coverage mandatory. Requirements differ by profession, regulator, and agreement. Texas gives clear examples of license-linked insurance rules.
Check both public rules and private contracts before buying. A commercial lease, client contract, loan agreement, or government contract may require insurance even when state law does not. Required limits can differ from one agreement to another.
Texas licensing and contract requirements
In Texas, licensed businesses may need liability insurance, E&O coverage, or a surety bond, depending on the profession and regulator. Texas licensing requirements include liability insurance for electrical contractors and E&O insurance for real estate inspectors.
Texas contracts can add their own insurance terms. Commercial leases, client contracts, loan agreements, and government contracts may require a policy or proof of coverage. Read the required limits and type of insurance in each agreement.
California workers’ compensation rule
As of February 6, 2026, California businesses with employees must carry workers’ compensation insurance. That rule covers a different exposure from professional liability: employee work injuries rather than client claims about services.
Check these four places for requirements:
- The relevant licensing board
- The state regulator for the profession
- The client contract
- The commercial lease
Workers’ compensation does not replace professional liability, and professional liability does not meet every contract requirement. Confirm the exact requirement with the relevant state regulator and read the contract’s limits before purchasing.
How Does Professional Liability Fit With Other Business Insurance?
Professional liability fills a different gap from the injury and property protection found in general liability and a BOP. A business owner policy, or BOP, commonly combines general liability, commercial property, and business income coverage. Each policy addresses a different set of losses.
A BOP does not automatically replace professional liability. Small business insurance may combine distinct policies based on the business’s operations. The right mix depends on the risks the company faces.
| Coverage type | Main exposure addressed | How it relates to professional liability |
|---|---|---|
| Professional liability | Claims of service errors causing financial harm | Addresses client claims about professional work |
| General liability | Third-party bodily injury and property damage | Addresses injury or property risks, not service errors |
| BOP | General liability, commercial property, business income | Combines common coverages but may not include E&O |
| Workers’ compensation | Employee work injuries | Addresses staff injuries, not client financial losses |
A BOP can bring basic coverages together, while professional liability addresses claims tied to services. Commercial property can cover certain property losses. Commercial auto addresses business vehicle risks, and workers’ compensation covers employee work injuries.
The Hartford customer data puts a typical BOP cost at $141 per month, or $1,687 per year. Those figures describe customer averages, not a universal quote. The business’s needs and policy terms still shape its coverage package.
Build the package around the risks the business actually has, rather than assuming one policy covers every claim.
Should an LLC Get Professional Liability Insurance?
An LLC should consider professional liability when a client could blame its work for a financial loss. The business structure does not remove insurance duties in a license, contract, or policy. Client work, not the company’s legal form, creates this exposure.
An LLC’s legal structure does not replace insurance obligations. A consulting LLC, for example, may face a claim that its advice caused a client financial harm. The business can consider coverage for that risk like any other service provider.
Check contracts and licensing rules that apply to the LLC’s services. A client may require proof of coverage even when no rule requires the policy. A legal entity alone does not pay defense costs or covered losses.
Employee coverage depends on the policy wording. Some policies may define covered employees or work in specific ways. Subcontractors may not be covered automatically, even when they help deliver the same service.
Ask the insurer how the policy treats each worker and subcontractor arrangement. Name every employee and subcontractor arrangement accurately when asking an insurer about covered work.
How Do You Get and Compare Professional Liability Quotes?
Prepare a concise description of your services and requested limits before requesting the first quote. You can get quotes directly from an insurer, through an agent, or through an independent broker. Local availability means the insurer writes policies in your state, not that it has a nearby office.
Compare quotes with matching limits, deductibles, and exclusions instead of choosing the lowest premium alone. That approach helps show whether a cheaper offer shifts more risk to the business. It also makes policy terms easier to compare.
Direct insurer, agent, or broker
Buying directly can offer an online application and purchase path. ERGO NEXT’s online quote process takes about 10 minutes, coverage begins after payment, and a certificate of insurance is available.
An agent can help with an insurer’s products and may guide an owner through a phone purchase. An independent broker can compare options from several insurers. Ask each contact how it handles questions and claims support.
What to have ready before requesting quotes
Gather these five details before you ask insurers for prices:
- Business services and the work clients receive
- Business location and states of operation
- Employee count
- Annual revenue
- Requested per-claim and aggregate limits
For a search for cheap business insurance for a small business, compare side-by-side quotes using the same limits, deductibles, and exclusions. A lower premium may carry a higher deductible or narrower coverage. Check which insurers are licensed and available in your state to find local options.
A certificate of insurance, or COI, documents active coverage and key details such as limits and effective dates. The COI is proof of insurance, not a replacement for the policy. Verify that the certificate of insurance shows the limits and effective dates required by the client or landlord.
When Should You Review or Change Your Policy?
A policy that matched last year’s services may not fit after the business adds a new service or location. Review coverage at the annual renewal, which commonly comes after a one-year policy term. Business changes can alter the work and risks the policy needs to address.
Review coverage when revenue, payroll, employee count, locations, or services change. New staff or a new service may change how much work the business does and who performs it. A move can also affect the policy’s stated location.
Updating a policy is different from switching insurers. A business may be able to adjust coverage with its current insurer as operations change. A new insurer can create a separate continuity issue for claims-made protection.
When changing a claims-made policy, arrange prior-acts coverage under the new policy or tail coverage under the old one. The new policy’s retroactive date can affect protection for earlier work. Keep the change from leaving a gap in reporting rights.
Review the policy after adding staff, opening a location, or changing the services clients receive. Before changing a claims-made policy, confirm in writing how earlier work remains covered.
Conclusion
A good fit is the policy that protects the work your business actually performs and satisfies the requirements it must meet. Price matters, but policy wording can determine which claims receive help. Claims-made coverage also needs continuity when a policy changes or ends.
Compare the policy wording as carefully as the price, and protect continuity for claims-made coverage. Gather your service list and any client or licensing requirements before requesting quotes. That gives insurers the details needed to offer comparable terms.
Gather your contracts and service details, then compare quotes with matching limits and deductibles.