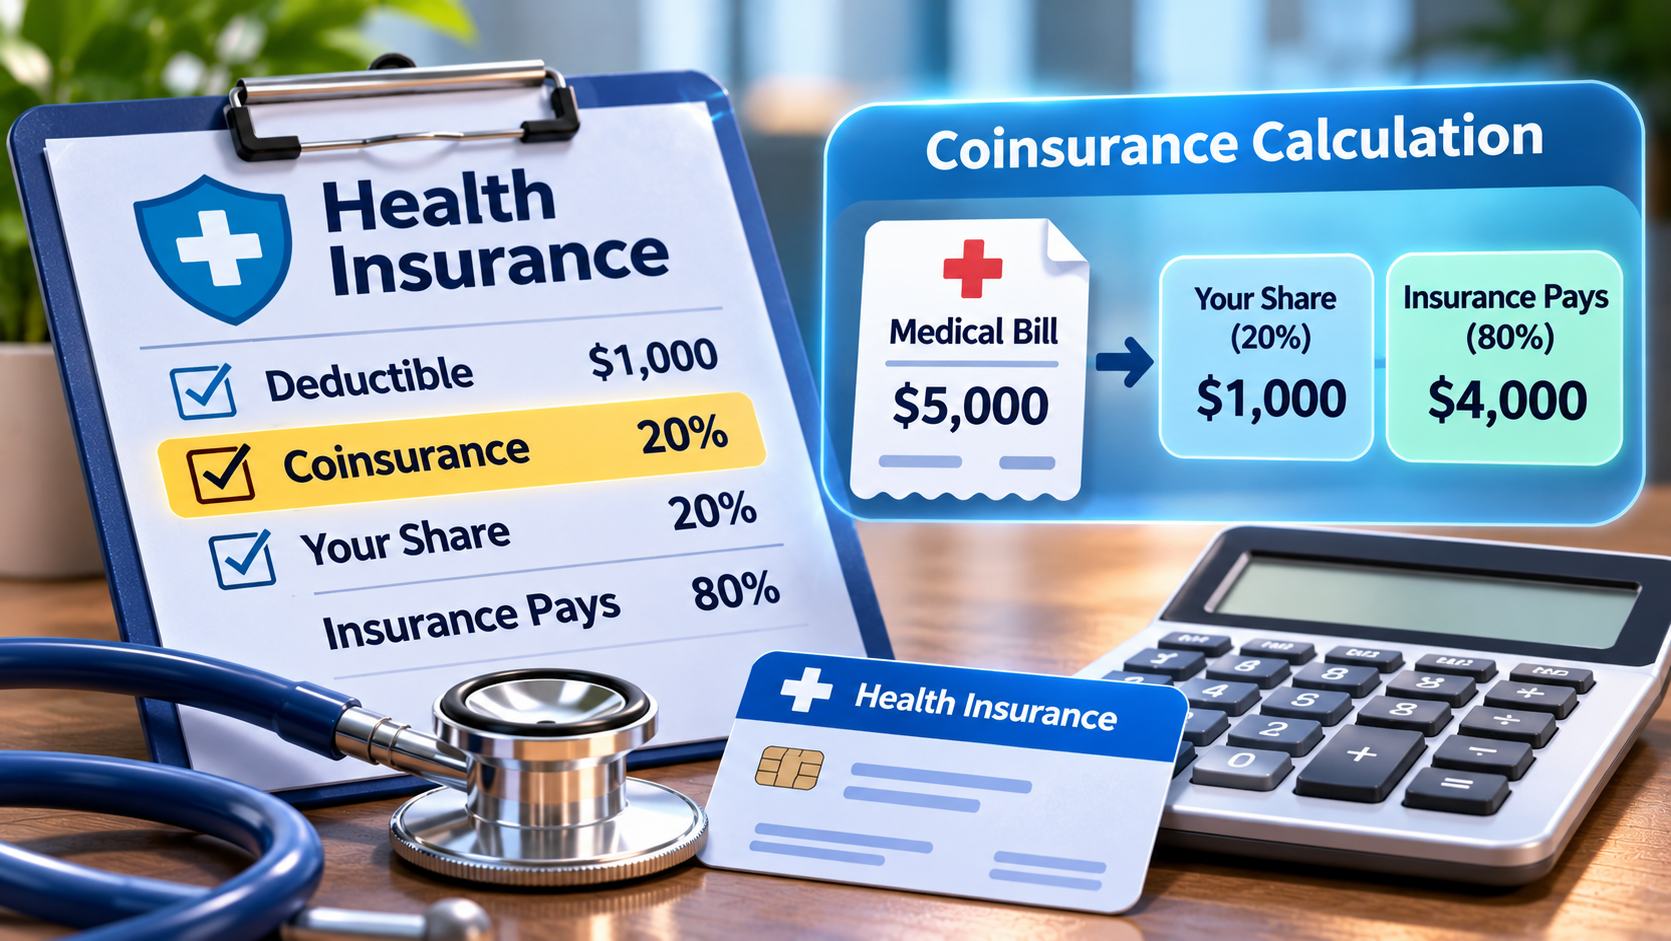
Health Insurance Coinsurance Calculations are a crucial aspect of understanding how medical costs are shared between insurers and insured individuals. Coinsurance, the percentage of costs that policyholders must pay after meeting their deductible, can significantly impact healthcare expenses. By grasping the intricacies of coinsurance, individuals can navigate their health plans more effectively and make informed decisions about their medical care.
This topic delves into the fundamental principles of coinsurance, illustrating how different health insurance plans structure their coinsurance percentages. We’ll explore common scenarios where coinsurance applies, as well as provide practical guidance on calculating payments and minimizing out-of-pocket costs.
Understanding the Concept of Coinsurance in Health Insurance
Coinsurance is a critical term in health insurance that describes the portion of costs that insured individuals are responsible for after meeting their deductible. Essentially, it is a cost-sharing mechanism between the insurer and the insured, ensuring that both parties contribute to healthcare expenses. This arrangement is designed to minimize over-utilization of medical services by encouraging patients to be more mindful of healthcare costs. Coinsurance is typically expressed as a percentage, representing the part of the medical bill that the policyholder must pay after the deductible has been satisfied.
In a typical health insurance plan, coinsurance percentages can vary significantly. Common structures include 80/20, 70/30, or even 60/40 arrangements. For example, in an 80/20 plan, the insurer covers 80% of the medical costs after the deductible, while the insured is responsible for the remaining 20%. This means if a medical procedure costs $1,000, and the deductible has been met, the insurer will pay $800, leaving the insured to pay $200 out of pocket. Different health insurance plans may have varying coinsurance rates depending on the type of care, such as inpatient versus outpatient services or emergency care versus regular office visits.
Common scenarios where coinsurance comes into play include hospital stays, surgeries, and specialist consultations. For instance, if a patient undergoes a surgery costing $10,000 and has a coinsurance rate of 20%, the insured would pay $2,000 after meeting their deductible. Another example is during a visit to a specialist. If the specialist charges $200 for a consultation and the coinsurance is set at 30%, the insured would pay $60, while the insurance company would cover the remaining $140. Understanding coinsurance is vital for consumers as it directly affects out-of-pocket expenses and informs financial planning related to healthcare needs.
Steps to Calculate Coinsurance Payments
Calculating coinsurance payments is an essential aspect of understanding how health insurance works and managing medical expenses. Coinsurance is the percentage of the medical bill that you are responsible for paying after meeting your deductible. Knowing how to calculate this accurately can help you plan for your healthcare costs effectively.
The process of calculating coinsurance payments involves a few simple steps. These steps ensure that you correctly determine your share of the medical expenses based on the total cost of care, your deductible, and your coinsurance rate.
Process for Calculating Coinsurance Payments
To accurately calculate your coinsurance payments, follow these steps:
1. Determine Total Medical Costs: This is the amount billed by the healthcare provider for services rendered.
2. Identify Your Deductible: This is the amount you must pay out-of-pocket before your insurance starts covering costs.
3. Subtract the Deductible from the Total Medical Costs: This will give you the amount that will be subject to coinsurance.
4. Apply the Coinsurance Rate: Multiply the remaining amount by your coinsurance percentage to find out how much you owe.
5. Calculate Your Total Payment: Add any additional fees or out-of-pocket expenses to arrive at your total payment.
Here’s a practical example to illustrate these steps:
– Total Medical Costs: $1,000
– Deductible Amount: $300
– Coinsurance Rate: 20%
Calculation Breakdown:
– Step 1: Identify Total Medical Costs: $1,000
– Step 2: Subtract Deductible: $1,000 – $300 = $700
– Step 3: Apply Coinsurance Rate: $700 * 20% = $140
– Total Payment: $300 (deductible) + $140 (coinsurance) = $440
To present various scenarios and their resulting coinsurance amounts, refer to the table below:
| Total Medical Costs | Deductible Amount | Coinsurance Rate | Coinsurance Payment |
|---|---|---|---|
| $1,000 | $300 | 20% | $140 |
| $2,500 | $500 | 30% | $600 |
| $750 | $200 | 15% | $82.50 |
| $1,500 | $400 | 25% | $275 |
These examples demonstrate how different medical costs, deductibles, and coinsurance rates can affect the total out-of-pocket expenses. Understanding these calculations allows you to better navigate your health insurance plan and budget for your healthcare needs.
The Role of Deductibles in Coinsurance Calculations
Understanding how deductibles interact with coinsurance is crucial for anyone navigating health insurance. Deductibles are the amounts that individuals must pay out-of-pocket for healthcare services before their insurance begins to cover costs. This can significantly influence the overall amount of coinsurance that a policyholder ends up paying, as the deductible must be satisfied before any coinsurance kicks in.
Deductibles impact the amount individuals pay in coinsurance by establishing a threshold that must be met first. Once the deductible is reached, the insurance plan will start to share the costs of eligible medical expenses, typically through coinsurance. For instance, if a policyholder has a $1,000 deductible and incurs $5,000 in medical expenses, they must first pay the $1,000 out-of-pocket. After meeting the deductible, if their coinsurance is set at 20%, they would then be responsible for 20% of the remaining $4,000, which amounts to an additional $800. Thus, their total out-of-pocket expense for the medical procedure in this scenario would be $1,800.
Example of Deductibles and Coinsurance Interaction
To illustrate this interaction further, consider a specific medical procedure, such as an MRI scan. Let’s assume the total cost of the MRI is $2,500, and the individual has the following plan details:
– Annual deductible: $1,000
– Coinsurance: 20%
– Out-of-pocket maximum: $5,000
In this example, the process unfolds as follows:
1. The individual pays the initial $1,000 to meet their deductible.
2. After the deductible is satisfied, the remaining cost of the MRI is calculated:
– Total cost of MRI: $2,500
– Amount after deductible: $2,500 – $1,000 = $1,500
3. With a 20% coinsurance rate applied to the remaining cost:
– Coinsurance amount: 20% of $1,500 = $300
4. Adding these amounts gives the individual a total out-of-pocket expense of:
– Total Expense = Deductible + Coinsurance = $1,000 + $300 = $1,300
This example illustrates how deductibles directly influence the coinsurance amount since costs are shared only after reaching the deductible.
Variations in Plan Handling of Deductibles and Coinsurance
Health insurance plans can vary significantly in how they structure deductibles and coinsurance. Here are some common variations:
– High Deductible Health Plans (HDHPs): These plans typically have higher deductibles but lower monthly premiums. Individuals may have to pay a considerable amount out-of-pocket before coinsurance applies.
– Low Deductible Plans: These plans often feature lower deductibles but may have higher premiums. Coinsurance applies sooner, which may be beneficial for those expecting frequent medical care.
– Preventive Services: Many plans cover certain preventive services like annual check-ups without requiring the deductible to be met first, meaning coinsurance may not apply at all for these services.
– Family vs. Individual Deductibles: Some plans have separate deductibles for individual members and a combined family deductible, which can affect how coinsurance is calculated for families.
These variations highlight the importance of understanding individual health plans and how deductibles and coinsurance interact to determine overall healthcare costs.
Comparing Coinsurance to Other Cost-Sharing Models
Cost-sharing models in health insurance play a crucial role in determining how much consumers will pay for medical services. Among these models, coinsurance, copayments, and deductibles are the most common. Each has its own structure and implications on out-of-pocket costs for policyholders, making it vital to understand how they differ and when they might be beneficial.
Coinsurance is a percentage of the total cost of a service that the insured pays after the deductible is met. Copayments, on the other hand, are fixed fees paid for specific services, while deductibles are the amount an insured must pay out-of-pocket before their insurance coverage kicks in. While all three methods aim to share costs between the insurer and the insured, they do so in distinct ways.
Differences and Similarities
Understanding the nuances between coinsurance, copayments, and deductibles can help consumers make informed decisions about their health insurance options. Here’s a breakdown of how each model operates:
– Coinsurance: Typically expressed as a percentage (e.g., 20% coinsurance), this model requires the insured to pay a portion of the cost after meeting their deductible. For instance, if a medical procedure costs $1,000 and the deductible is met, the insured would pay $200 if they have a 20% coinsurance.
– Copayment: This is a fixed amount paid for specific services, regardless of the total cost of care. For example, a visit to a primary care physician might require a $30 copayment, which would remain constant regardless of the visit’s total cost.
– Deductible: This is a predetermined amount that must be paid out-of-pocket before the insurance begins to cover costs. For instance, if a policy has a $1,000 deductible, the insured must pay this amount in full before their insurance starts covering coinsurance or copayments.
### Advantages and Disadvantages of Each Model
Each cost-sharing model has its pros and cons, influencing consumer choice based on their healthcare needs and financial situation. The following points summarize these factors:
#### Coinsurance
– Advantages:
– Encourages cost-conscious decisions as the insured pays a percentage of the cost.
– Can lead to lower monthly premiums compared to plans with fixed copayments.
– Disadvantages:
– Unpredictable out-of-pocket costs, especially for high-cost medical services.
– Could lead to significant expenses if a major health event occurs.
#### Copayment
– Advantages:
– Predictable costs make budgeting easier for routine care.
– Fixed amounts can encourage timely visits to healthcare providers.
– Disadvantages:
– May not cover the full cost of services, leading to unexpected out-of-pocket expenses.
– Can result in higher overall costs if many services are needed.
#### Deductible
– Advantages:
– Typically lower premium costs, which can benefit those with minimal healthcare needs.
– Provides a clear threshold for when insurance coverage begins.
– Disadvantages:
– High upfront costs before benefits are activated, which can be challenging for low-income individuals.
– May discourage necessary medical care until the deductible is met.
In various situations, one cost-sharing model can be more advantageous than the others. For example, individuals who expect to have high medical expenses may benefit more from a plan with low coinsurance rates after a deductible, while those who prefer predictable costs may lean towards a copayment structure. Additionally, younger, healthier individuals might opt for higher deductibles with lower premiums, reflecting their lower anticipated healthcare needs. Understanding these nuances will allow consumers to choose plans that best suit their financial situation and healthcare expectations.
Common Misconceptions About Coinsurance
Many individuals tend to misunderstand the concept of coinsurance in health insurance, often leading to confusion regarding their financial responsibilities when accessing healthcare services. This misunderstanding can significantly impact their decisions about choosing plans and seeking necessary medical care. By clarifying these misconceptions, consumers can make more informed choices that align with their healthcare needs and financial situations.
One prevalent misconception about coinsurance is the belief that it is the same as a copayment. While both terms relate to cost-sharing, they function differently. A copayment is a fixed amount paid for a specific service at the time of care, while coinsurance is a percentage of the total cost that the insured must pay after meeting their deductible. This distinction is crucial because it affects how much individuals ultimately pay out-of-pocket for their healthcare services.
Implications of Misunderstanding Coinsurance
Misunderstanding coinsurance can lead to various implications for consumers, particularly in how they approach healthcare decisions. Individuals may overlook the importance of understanding their plan’s coinsurance structure, which can result in unexpected medical bills. Awareness of how coinsurance works is essential for planning finances and making choices about when and where to seek care.
Statistics reveal that a significant number of consumers are not fully aware of their insurance plan details, including coinsurance. A survey conducted by the Kaiser Family Foundation found that approximately 30% of insured adults did not understand their coinsurance rates, which directly impacts their healthcare choices. Many may defer necessary treatments or avoid seeking care altogether due to fear of high costs, believing they will bear a larger financial burden than actual coinsurance rates would dictate.
In summary, a clear understanding of coinsurance can empower consumers, allowing them to navigate their health insurance plans more effectively and utilize healthcare services without the fear of unexpected expenses. By educating themselves on coinsurance and its implications, individuals can enhance their decision-making processes and overall satisfaction with their health insurance coverage.
The Impact of Coinsurance on Healthcare Costs
Coinsurance significantly influences the financial landscape for insured individuals, acting as a crucial factor in determining out-of-pocket expenses for healthcare services. This cost-sharing model can lead to varying levels of financial responsibility depending on the percentage set by the insurance plan. Understanding how coinsurance impacts overall healthcare costs is essential for managing personal finances effectively.
Coinsurance is typically expressed as a percentage of the total healthcare costs that insured individuals must pay after meeting their deductible. This model can lead to increased overall healthcare expenses, particularly for patients requiring frequent or costly medical services. High coinsurance rates can create financial strain over time, as the burden of medical expenses shifts more toward the insured individual.
Long-term Financial Implications of High Coinsurance Rates
The long-term financial implications of having a high coinsurance rate can be profound. Patients may face significant costs that accumulate over the years, particularly if they encounter ongoing health issues or require expensive treatments. As a result, planning for healthcare expenses becomes critical. A study by the Kaiser Family Foundation reveals that individuals with high coinsurance rates tend to defer necessary medical treatments and services, thereby risking their health and potentially incurring even greater costs down the line.
To illustrate the potential financial impact, the following table compares average costs incurred by insured individuals under low and high coinsurance rates over a span of five years:
| Year | Average Annual Healthcare Costs (Low Coinsurance – 10%) | Average Annual Healthcare Costs (High Coinsurance – 30%) |
|---|---|---|
| 1 | $5,000 | $1,500 |
| 2 | $5,500 | $1,650 |
| 3 | $6,000 | $1,800 |
| 4 | $6,500 | $1,950 |
| 5 | $7,000 | $2,100 |
| Total (5 Years) | $34,000 | $9,000 |
In this illustration, the difference in payment responsibilities becomes evident. Individuals with a high coinsurance rate may find even routine medical expenses burdensome, especially when faced with serious health issues. The accumulated costs over five years not only highlight the immediate financial outlay but also stress the importance of considering coinsurance rates when selecting health insurance plans. Being informed can empower individuals to make choices that align better with their health needs and financial capabilities.
Strategies for Minimizing Coinsurance Payments
Coinsurance payments can significantly impact the overall cost of healthcare. Understanding how to effectively minimize these payments is essential for consumers looking to manage their healthcare expenses better. By employing certain strategies, individuals can navigate their health insurance plans more efficiently and reduce their financial burden.
Preventive care is one of the most effective strategies for reducing overall healthcare costs, including coinsurance. Regular check-ups and screenings can help identify potential health issues early on, leading to less severe conditions that require expensive treatments. Engaging in preventive care not only keeps individuals healthier but also minimizes the likelihood of incurring high coinsurance payments associated with more serious health issues down the line.
Utilizing In-Network Providers
One critical approach to reducing coinsurance payments is to use in-network providers. Insurance plans typically have a network of doctors and facilities that have agreed to provide services at discounted rates. By opting for these providers, consumers can significantly lower their out-of-pocket expenses. This strategy is vital since out-of-network care can result in much higher coinsurance rates.
Understanding Your Plan’s Benefits
Familiarity with the specific benefits and limitations of a health insurance plan can empower consumers to make informed decisions. Each plan has different coverage levels, coinsurance percentages, and exclusions that can affect costs. By thoroughly reviewing plan documents, individuals can identify the most cost-effective services and avoid unnecessary charges.
Leveraging Health Savings Accounts
Health Savings Accounts (HSAs) are tax-advantaged accounts that help individuals save for medical expenses. Contributions to HSAs are made pre-tax, and the funds can be used for qualified medical expenses, including those subject to coinsurance. Using HSAs effectively can alleviate the financial strain of coinsurance payments and provide long-term savings for healthcare.
Staying Informed About Prescription Costs
Prescription medications can contribute to high coinsurance payments, especially for brand-name drugs. It’s beneficial for consumers to be proactive about medication costs. Engaging with pharmacists to find generic alternatives or utilizing drug discount programs can lead to significant savings. Furthermore, understanding formulary tiers within insurance plans can help consumers select the most cost-effective options.
Resources for Understanding and Managing Coinsurance
Utilizing available resources can enhance consumers’ understanding and management of their coinsurance responsibilities. Several tools and resources are invaluable:
- Insurance Provider Websites: Many insurance companies provide calculators and plan details that help consumers understand their coinsurance obligations.
- Healthcare Cost Estimation Tools: Websites that allow consumers to estimate healthcare costs based on their insurance plan can aid in planning ahead for expenses.
- Patient Advocacy Groups: Organizations often offer guidance on navigating insurance plans and understanding coinsurance responsibilities.
- Financial Counseling Services: Some hospitals and health systems provide financial counseling to help patients understand their bills and insurance coverage.
Conclusive Thoughts
In summary, understanding Health Insurance Coinsurance Calculations empowers individuals to take control of their healthcare expenses. By recognizing how coinsurance interacts with deductibles, comparing it with other cost-sharing models, and debunking common misconceptions, consumers can make informed choices that best fit their financial situations. With effective strategies and resources at hand, minimizing coinsurance payments becomes an achievable goal, leading to a more sustainable approach to healthcare costs.
FAQ Resource
What is the difference between coinsurance and copayment?
Coinsurance is a percentage of the total cost that you pay after meeting your deductible, while a copayment is a fixed amount you pay for specific services at the time of the visit.
How does coinsurance affect my insurance premiums?
Typically, plans with higher coinsurance rates may have lower premiums, while those with lower coinsurance rates usually come with higher premiums.
Is coinsurance applied before or after the deductible?
Coinsurance is applied after you have met your deductible. You are responsible for the deductible amount first before coinsurance kicks in.
What happens if I reach my out-of-pocket maximum?
Once you reach your out-of-pocket maximum, your insurance will cover 100% of your covered medical expenses for the remainder of the policy year.
Can I negotiate my coinsurance rates?
No, coinsurance rates are set by the insurance policy and cannot typically be negotiated, but you can choose different plans that offer varying coinsurance rates.