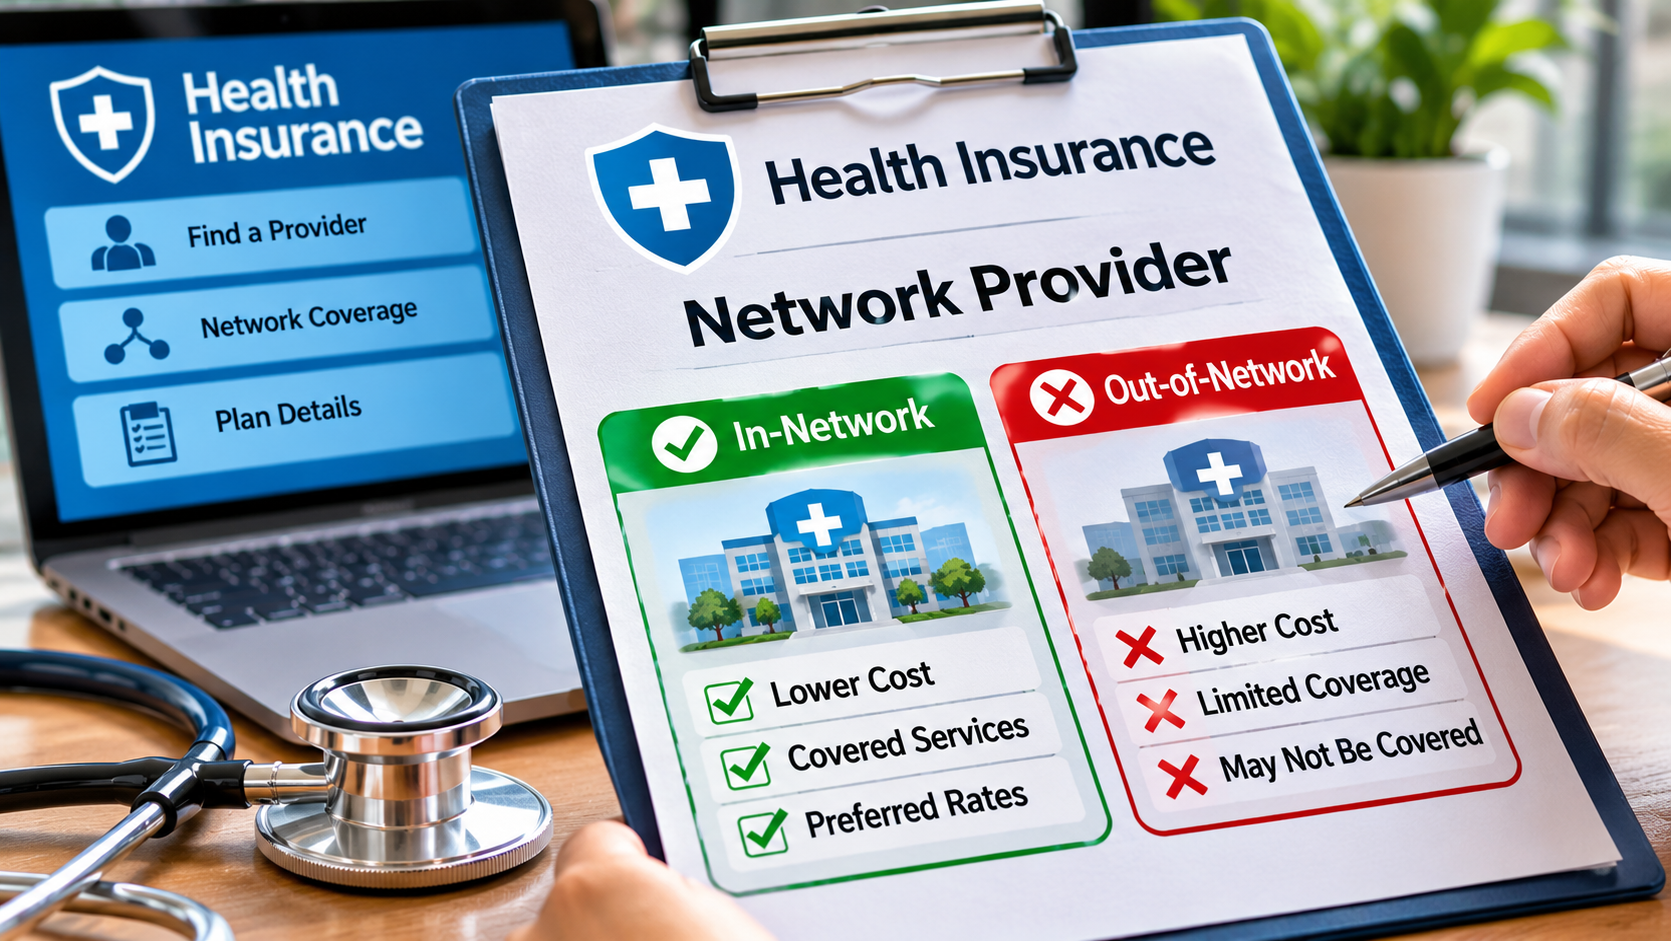
Health Insurance Network Provider Restrictions play a crucial role in shaping the healthcare choices available to consumers. Navigating the landscape of health insurance can often feel overwhelming, especially when it involves understanding various network plans like HMO, PPO, and EPO. Each of these plans presents unique features and limitations that can significantly impact a patient’s access to care and provider options. By grasping these concepts, consumers can make informed decisions about their healthcare coverage.
In this context, terms like “in-network” and “out-of-network” become essential benchmarks for understanding your options and potential costs. Whether you’re seeking routine care or specialized treatment, knowing how network restrictions work can help you avoid unexpected expenses and ensure you receive the best possible care. This discussion aims to demystify these restrictions and guide you through the intricacies of health insurance networks.
Understanding Health Insurance Network Provider Restrictions
Health insurance network provider restrictions are an essential aspect of how health insurance plans operate. These restrictions dictate which healthcare providers a policyholder can see for their medical needs. Understanding these limits is crucial, as they significantly influence consumer choices, access to care, and out-of-pocket expenses. Network restrictions are designed to control costs for both insurers and insured individuals, but they can also constrain access to preferred doctors and specialists.
There are several types of health insurance network plans, each with its own structure and implications for patient care. The three most common types are Health Maintenance Organizations (HMOs), Preferred Provider Organizations (PPOs), and Exclusive Provider Organizations (EPOs).
Types of Network Plans
Each type of network plan has distinct features that affect how patients seek care and which providers they can use.
– Health Maintenance Organization (HMO): An HMO requires members to select a primary care physician (PCP) who coordinates their healthcare. Members must get referrals from their PCP to see specialists. This model often results in lower premiums and out-of-pocket costs. For example, an HMO plan might cover all preventive care visits at no cost but requires a referral to see an orthopedic surgeon.
– Preferred Provider Organization (PPO): A PPO offers more flexibility than an HMO. Members can see any provider but receive higher benefits when using in-network providers. They do not need referrals to visit specialists. For instance, a patient may choose to see an out-of-network cardiologist, but they will pay a higher co-insurance rate compared to an in-network provider.
– Exclusive Provider Organization (EPO): An EPO is similar to a PPO but does not cover out-of-network care except in emergencies. Patients can see any specialist without a referral, but they must stay within the network. An example is an EPO that has a robust network of specialists, allowing patients to access multiple services without additional costs for out-of-network care.
Understanding terms like “in-network” and “out-of-network” is vital when navigating these plans. In-network providers are those who have contracted with the insurance company, resulting in lower costs for the insured. Conversely, out-of-network providers do not have such agreements, leading to higher out-of-pocket expenses. This distinction is critical for consumers as it affects their overall healthcare costs and access to necessary treatments.
The Role of Health Care Providers in Network Restrictions
Healthcare providers are integral to the functioning of health insurance networks. These providers, which include hospitals, clinics, and specialized medical practitioners, must meet certain criteria to become part of an insurance network. This relationship is not only beneficial for insurers, but also crucial for the patients who depend on these providers for their healthcare needs.
To join a health insurance network, providers typically must adhere to a range of standards and regulations established by the insurer. The selection process often involves evaluating the provider’s qualifications, the quality of care they offer, and their adherence to guidelines set forth by the insurance company. Factors such as board certifications, the range of services provided, and previous patient outcomes play a significant role in this evaluation. Additionally, providers must agree to the reimbursement rates set by the insurer, which can vary widely based on various factors.
Criteria for Joining Health Insurance Networks
The criteria for healthcare providers to gain entry into an insurance network are multifaceted and essential for maintaining the quality of care. Understanding these criteria can shed light on the complexities involved:
- Licensure and Certification: Providers must hold valid licenses and relevant certifications that comply with state and federal regulations.
- Quality of Care Metrics: Insurers examine patient outcome data, including readmission rates and patient satisfaction scores, as indicative of a provider’s quality.
- Cost Structure: The financial viability of the provider is assessed through their ability to operate efficiently within the reimbursement framework proposed by the insurer.
- Network Needs: Insurers may prioritize providers based on geographic location, specialty services, and the overall need for specific healthcare services in a given area.
- Compliance with Protocols: Providers must demonstrate adherence to clinical guidelines and protocols, ensuring they deliver care that aligns with the insurer’s standards.
The implications of provider restrictions extend beyond the insurance companies and affect both patients and healthcare professionals significantly.
Implications of Provider Restrictions
Provider restrictions can lead to a limited choice of healthcare options for patients, impacting their ability to receive care from preferred providers. This restriction may result in higher out-of-pocket costs if patients seek care outside of their network. Additionally, these constraints can create barriers for healthcare professionals seeking to expand their patient base or collaborate with other providers, ultimately affecting the overall quality of care delivered.
For healthcare providers, being part of a network can yield benefits such as a steady stream of patients and guaranteed payments. However, these advantages come with challenges, especially regarding the negotiations with insurers.
Negotiation Process Between Health Insurers and Healthcare Providers
Negotiations between health insurers and healthcare providers are crucial for establishing mutually beneficial agreements. Various factors can influence the outcomes of these discussions:
- Market Dynamics: Competition among providers and insurers can affect negotiation power, with providers in high-demand specialties often able to negotiate better terms.
- Cost Considerations: Insurers aim to control costs and may push for lower reimbursement rates, while providers strive to secure fair compensation for their services.
- Value-Based Care Models: Insurers are increasingly incentivizing providers to focus on quality outcomes rather than volume, which can redefine negotiation dynamics.
- Patient Population: The demographics and health needs of a provider’s patient population can influence negotiations, particularly in regions with high incidences of chronic conditions.
- Regulatory Environment: Changes in healthcare laws and policies can also affect negotiations, as providers must adapt to new reimbursement models or compliance requirements.
Overall, the intricate relationships built through these negotiations ultimately shape the landscape of healthcare delivery, impacting patient access and quality of care in significant ways.
Effects of Network Restrictions on Patient Care
Network restrictions in health insurance can significantly impact the quality of care patients receive, often limiting their access to specialists and necessary treatments. These constraints arise when insurance companies create a network of preferred providers, which can lead to complexities in receiving timely and appropriate care. Patients might find themselves navigating a maze of referrals, approvals, and out-of-pocket costs that can detract from their overall health experience.
When patients are restricted to a certain network, they may face challenges in accessing specialized treatments. For instance, if a patient requires a specific type of surgery that is only available at a non-network hospital, they may be forced to choose between facing substantial out-of-pocket expenses or forgoing necessary care altogether. The quality of treatment can also be affected as patients may have to settle for less experienced providers due to the limitations imposed by their insurance.
Challenges Faced Due to Network Limitations
The impact of network restrictions can be illustrated through several case studies. One notable example involves a patient diagnosed with a rare condition requiring specialized care from a renowned expert outside of their insurance network. Despite the expert’s proven track record, the patient’s insurance refused coverage, forcing them to seek treatment elsewhere, delaying necessary intervention and potentially worsening their health situation. This scenario highlights the critical importance of flexibility in healthcare access.
Another case involves a patient needing emergency care. In numerous instances, patients are unable to choose their healthcare provider in urgent situations, which can lead to unfavorable outcomes. A study published in the *American Journal of Emergency Medicine* found that patients taken to out-of-network emergency rooms faced higher costs and complications due to lack of immediate access to their primary care physician or specialist. The inability to connect with familiar providers in such dire situations can compromise the quality of care delivered, ultimately impacting recovery times and patient satisfaction.
In summary, network restrictions pose significant barriers to accessing timely and appropriate care, affecting patient outcomes and the overall healthcare experience. The necessity for reform in this area is evident as patients continue to navigate the complexities introduced by insurance networks, often at the expense of their health and well-being.
Consumer Rights and Advocacy Regarding Network Restrictions
Navigating health insurance network restrictions can be challenging, but consumers have specific rights that empower them to advocate for their needs. Understanding these rights is crucial for ensuring access to necessary healthcare services without undue barriers. This section delves into the rights consumers hold and how they can effectively advocate for themselves in the face of network restrictions.
Consumers have the right to receive clear information regarding their health insurance plans, including network restriction details. This transparency helps individuals make informed decisions about their healthcare providers and services. It is also essential for consumers to know that they can appeal decisions made by their health insurance provider if they believe access to care has been unjustly denied. Advocacy plays a significant role in this process.
Rights of Consumers with Network Restrictions
Understanding the rights of consumers in the context of network restrictions is vital. Here are key rights that consumers should be aware of:
- Right to Information: Consumers have the right to receive detailed information about their health insurance plans, including which providers are in-network and out-of-network.
- Right to Appeal: If a claim is denied due to network restrictions, consumers have the right to appeal this decision, asking for a review of their case.
- Right to Emergency Services: Consumers are entitled to receive emergency services regardless of network restrictions, ensuring timely care in critical situations.
- Right to Non-Discrimination: Health plans cannot discriminate based on race, gender, or disability when determining access to care.
- Right to Privacy: Consumers have the right to confidentiality regarding their health information, including discussions about network restrictions.
Resources for Navigating Network Restrictions
A variety of resources and organizations are available to assist consumers in understanding their rights and navigating the complexities of network restrictions. Utilizing these resources can enhance a consumer’s ability to advocate for their care effectively.
- The National Association of Insurance Commissioners (NAIC) provides resources to help consumers understand their insurance rights and file complaints.
- The American Medical Association (AMA) offers guidance and support for patients dealing with insurance restrictions.
- State insurance departments often have consumer assistance programs that offer help in understanding network restrictions and filing appeals.
- Consumer Reports Health provides insights and reviews of various health plans, helping consumers make informed choices.
- The Patient Advocate Foundation works to ensure access to care for patients, providing resources for appeals and advocacy.
Filing Complaints and Appealing Decisions
In cases where consumers encounter issues with network restrictions, knowing how to file complaints or appeal decisions is essential. Here’s a step-by-step guide for consumers:
- Review the Policy: Start by reviewing your health insurance policy. Understand the specific network restrictions and the details of the denial.
- Gather Documentation: Collect all relevant documents, including claims, denial letters, and any correspondence with the insurance provider.
- Contact Customer Service: Reach out to your insurance company’s customer service line to discuss the issue. Make sure to document the date, time, and the name of the representative you speak with.
- Write an Appeal Letter: Draft a formal appeal letter that includes your details, policy number, the nature of your appeal, and any supporting documents. Clearly state your case and the outcome you seek.
- Submit the Appeal: Send your appeal letter and documentation to the address provided in your policy. Ensure you keep copies of everything for your records.
- Follow Up: After submitting your appeal, follow up with the insurer to confirm they received your appeal and inquire about the timeline for a decision.
- Seek Assistance: If the appeal is denied, consider reaching out to consumer advocacy organizations for further assistance.
Future Trends in Health Insurance Networks
As the healthcare landscape continues to evolve, health insurance networks are adapting to new challenges and opportunities. The convergence of technology, consumer demands, and regulatory changes is reshaping the way health insurance providers operate. Emerging trends indicate a shift towards more flexible network arrangements that prioritize patient access to care while optimizing costs for providers and payers alike.
The integration of technology and telemedicine is at the forefront of this transformation. With advancements in digital health solutions, health insurance networks are beginning to reconsider traditional provider restrictions. These changes aim to enhance care delivery, improve patient outcomes, and expand access to necessary services in a more efficient manner.
Role of Technology and Telemedicine
Technology is playing a pivotal role in redefining health insurance networks. Telemedicine, in particular, has gained significant traction, especially following the COVID-19 pandemic. Insurers are increasingly recognizing the value of virtual care in reducing barriers to access, leading to a re-evaluation of provider restrictions.
Key impacts of technology on health insurance networks include:
- Enhanced patient access: Telemedicine allows patients to consult with providers remotely, which can be especially beneficial in rural or underserved areas.
- Cost efficiency: Virtual visits often have lower overhead costs, which can result in reduced premiums for consumers and better reimbursement rates for providers.
- Improved data analytics: Advanced technology enables insurers to collect and analyze health data more effectively, facilitating personalized care plans and proactive management of chronic conditions.
- Streamlined processes: Automation in claims processing and patient management systems is reducing administrative burdens, allowing providers to focus more on patient care.
Innovative Models in Health Insurance Networks
Various innovative models are being tested and implemented that aim to reduce provider restrictions while maintaining high standards of care. These models capitalize on the integration of technology and emphasize collaboration among stakeholders.
Examples include:
- Accountable Care Organizations (ACOs): These groups of healthcare providers coordinate care to improve quality and reduce costs, often allowing for more flexibility in provider selection.
- Direct Primary Care (DPC): In this model, patients pay a flat fee to their primary care provider for a range of services, bypassing traditional insurance limitations and allowing for personalized care.
- Value-Based Care: This approach ties reimbursement to the quality of care provided rather than the quantity, encouraging providers to focus on patient outcomes rather than volume of services rendered.
- Integrated Behavioral Health: This model incorporates mental health services into primary care teams, expanding access to mental health providers and reducing stigma.
The future of health insurance networks is poised for significant change as these trends gain momentum. By leveraging technology and embracing innovative care models, health insurance providers can navigate the complexities of modern healthcare while enhancing access and quality of care for patients.
The Economic Implications of Network Provider Restrictions
Network provider restrictions play a significant role in shaping the economic landscape of healthcare. These restrictions often lead to a complex interplay of financial consequences that affect insurers, providers, and consumers alike. Understanding these implications is crucial for stakeholders involved in the healthcare system, as it influences pricing, access to care, and overall healthcare quality.
The financial consequences of network restrictions are multifaceted. Insurers often experience reduced costs when negotiating with in-network providers, which can lead to lower premiums for consumers. However, these savings can come at the expense of patients who may face limited choices in their healthcare options. On the other hand, out-of-network providers may charge higher fees, leading to increased out-of-pocket expenses for consumers. This can hinder access to necessary medical care, particularly for those with lower incomes.
Comparative Costs of In-Network and Out-of-Network Healthcare Services
When analyzing the cost differences between in-network and out-of-network services, it becomes evident that the financial implications can be substantial. For instance, a common procedure such as an MRI can vary dramatically in cost based on the network status of the provider. According to recent studies, an MRI performed at an in-network facility could cost a patient approximately $500, while the same procedure at an out-of-network provider could soar to $1,500 or more.
This disparity in pricing not only affects individual budgets but can also lead to broader economic repercussions. Here are some key points to consider regarding the cost dynamics of network provider restrictions:
- In-network services typically enjoy negotiated rates that are lower than out-of-network charges, providing financial relief to consumers.
- Out-of-network services can lead to surprising bills that result in financial strain, especially for unexpected medical emergencies.
- Insurance plans may impose higher deductibles or co-pays for out-of-network services, discouraging patients from seeking necessary care.
- Prolonged reliance on out-of-network services can lead to increased overall healthcare spending in a community, affecting local economic health.
Network restrictions can have profound effects on overall healthcare spending, influencing not just individual consumers but entire communities as well. A study from the Health Affairs journal noted that communities with restrictive network policies often see higher healthcare costs due to the limited number of available providers, which can lead to inflated prices for services. This creates a challenging environment for local economies, as higher healthcare costs can reduce disposable income and affect consumer spending in other sectors.
“Network restrictions can create a ripple effect in communities, influencing not only individual healthcare costs but also the economic stability of local businesses.”
In summary, the economic implications of network provider restrictions are significant, impacting costs for insurers, providers, and consumers and contributing to broader trends in healthcare spending and community economic health.
Conclusive Thoughts
In conclusion, understanding Health Insurance Network Provider Restrictions is vital for anyone navigating the complexities of healthcare coverage. As we’ve explored, these restrictions not only affect patient care but also carry significant economic implications for both consumers and providers. By advocating for your rights and staying informed about emerging trends in healthcare, you can better manage your health insurance choices. Remember, knowledge is power in ensuring you receive the care you deserve.
FAQ Resource
What does “in-network” mean?
“In-network” refers to healthcare providers or facilities that have contracted with your insurance plan to provide services at reduced rates.
Can I see an out-of-network provider?
Yes, but you may incur higher costs and may need to file claims for reimbursement.
How do I find out if a provider is in-network?
You can typically check your insurance company’s website or call their customer service for a list of in-network providers.
What are the consequences of using an out-of-network provider?
Using an out-of-network provider may lead to higher out-of-pocket expenses and limited coverage for services rendered.
Can network restrictions change?
Yes, network restrictions can change based on negotiations between insurers and providers, and it’s important to stay updated on your plan’s network status.